Woman’s Rs 25,000 rebate denied under new regime for capital gains; what ITAT said
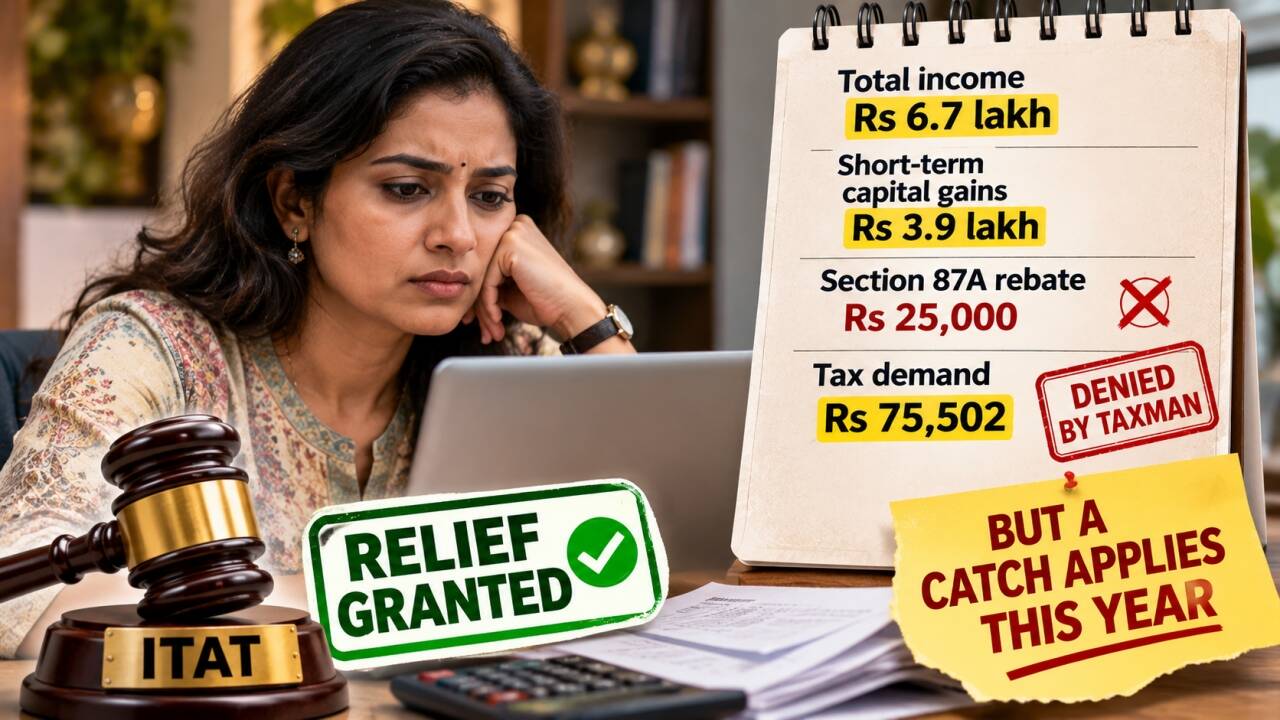
She argued that Section 87A nor Section 115BAC(1A) expressly barred the rebate merely because part of the taxpayer’s income was taxable under Section 111A. (Image for representative purpose only)
Are your short-term capital gains also eligible for a rebate if your overall income falls below Rs 12 lakh? A taxpayer who earned short-term capital gains from listed equity shares has won a dispute over a Rs 25,000 income tax rebate after the Income Tax Appellate Tribunal (ITAT), Hyderabad, held in her favour.The ITAT decision was regarding the availability of rebate under Section 87A of the Income-tax Act, 1961 (the ‘Act’), against tax payable on short-term capital gains arising from the transfer of equity shares taxable under Section 111A of Act.In its November 6, 2026, order, the tribunal ruled that Section 87A of the Income Tax Act, 1961, did not expressly prohibit the rebate in cases where income included short-term capital gains taxable at a special rate under Section 111A.
However, there is a catch.
What the case is about
A woman filed her income tax return for assessment year 2025-26, declaring a total income of Rs 6,77,511. This included short-term capital gains of Rs 3,97,511 arising from the transfer of listed equity shares. Such gains are taxable u/s 111A of the Act at a special rate of tax.She opted for the new tax regime under Section 115BAC(1A) and claimed a rebate of Rs 25,000 under Section 87A. However, when the Centralised Processing Centre (CPC), Bengaluru, processed her return, it determined a tax payable at Rs 75,502 without allowing the rebate.
The assessee challenged the denial before the Commissioner of Income Tax (Appeals). The first appellate authority rejected her explanation and upheld the denial. She then approached the Hyderabad bench of the ITAT.Her authorised representative argued that neither Section 87A nor Section 115BAC(1A) expressly barred the rebate merely because part of the taxpayer’s income was taxable under Section 111A.The representative also relied on two earlier tribunal decisions: Jayshreeben Jayantibhai Palsana v. ITO, decided by the ITAT Ahmedabad bench, and Pushpa Prakash Misar v. ITO, decided by the ITAT Mumbai bench. Jayendran’s counsel additionally cited the Bombay High Court decision in Chamber of Tax Consultants v. DGIT (Systems).The Revenue opposed the appeal. Its representative relied on CBDT Circular No. 13/2025, dated September 19, 2025, and argued that the rebate was not applicable to taxpayers opting for the new tax regime under Section 115BAC(1A). The department maintained that the lower authorities had correctly rejected the claim.
Why did ITAT rule in favour of assessee?
Tanu Gupta, Partner at Mainstay Tax Advisors LLP says that this judgement is important for the interpretation of Section 87A and the extent to which the rebate can be restricted by Circular No.
13/2025 dated September 19, 2025 issued by the CBDT.“ITAT was of the opinion that AO and CIT(A) did not have any other reason to disallow the tax rebate u/s 87A of the Act from the tax liability which included tax on short-term capital gains u/s 111A at a special rate,” she says.Further, on observing the plain language of Section 87A and its provisos, the ITAT was of the opinion that there is no restriction to claim rebate u/s.87A of the Act where the assessee satisfies the other prescribed conditions, such as income being under the applicable threshold even if it includes income taxable at special rate under Section 111A of the Act.“The Tribunal's decision also relies on past judgments. It was held that there is no express restriction to claim rebate u/s.87A of the Act even in a case of tax payment under the new regime of taxation as per provisions of Sec.115BAC(1A) of the Act,” Gupta tells TOI.
“The ruling is a welcome development for taxpayers, particularly for earlier assessment years, as it clarifies that the eligibility for tax rebate must be decided based on the provisions of the Income-tax Act and not restricted by administrative circulars or changes in the return filing utility.
It also reinforces the principle that a circular cannot take away a benefit that is available under the Act,” she adds.However, Gupta cautions that taxpayers should note that the position changes from FY 2025-26 onwards, as the Finance Act, 2025 has expressly restricted the Section 87A rebate to tax calculated at the specified slab rates. “Accordingly, the rebate will no longer be available against tax payable on special-rate income, including short-term capital gains under Section 111A,” she concludes.Hence, even though ITAT ruled in favour of the assessee for that particular assessment year, taxpayers should not that this rebate is no longer applicable from this year.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.