SA must ask who really benefits from a mining boom
This week, Daily Maverick reported on the improving relationship between the Minerals Council South Africa and the Department of Mineral and Petroleum Resources, with new work streams aimed at unlocking investment, addressing “competitiveness gaps” and ensuring what industry regards as a successful outcome to the Mineral Resources Development Amendment Bill.
There is nothing inherently wrong with the government and the mining industry talking to one another, nor with South Africa trying to improve infrastructure, fix its licensing system or attract investment. The concern lies elsewhere.
South Africa should be worried that a period of extraordinary profitability is once again being treated as evidence that we need to accelerate and deepen essentially the same model of extraction that has already helped produce one of the most unequal societies in the world.
Who benefits in SA from mineral profitability?
The latest PwC SA Mine 2026 report should therefore be read not simply as a good-news story about mining recovery, but as an invitation to ask a much more fundamental question: what has decades of mineral profitability actually produced for South Africa, and for whom?
Among the major mining companies tracked by PwC, revenue increased from R569-billion to R786-billion in a single year. Earnings before interest, taxes, depreciation and amortisation (ebitda) rose from R122-billion to R279-billion, net profit jumped from R65-billion to R185-billion, free cash flow increased from R75-billion to R201-billion, and shareholders received R82-billion during the year. A further R70.27-billion in dividends had already been declared after the reporting date.
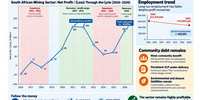
The 10-year picture is even more revealing.
PwC’s historical series records losses in 2016 and 2018, but those downturns were followed by very substantial profits, including R88-billion in 2020, R208-billion in 2021, R206-billion in 2022, R108-billion in 2023 and R185-billion in 2026. Across the period 2016–2026, the companies reflected in PwC’s series generated almost R1-trillion in cumulative net profit, while distributing roughly R691-billion to shareholders.
That is not the picture of an industry that has been structurally incapable of generating wealth. It is the picture of an industry that has generated immense wealth through repeated cycles of boom and downturn.
The real question is what happened to that wealth.
This question matters because Oxfam South Africa’s newly released report, Hoarded Wealth, Dignity Denied, paints a stark picture of the economy in which this mineral wealth has been produced. Oxfam estimates that the richest 1% of South Africans now own more than half of all the country’s private wealth – 54.9% in 2024 – an even greater share than they held at the dawn of democracy in 1994, while the bottom half of the population held negative wealth, meaning their debts exceeded their assets. The richest 10% held 85.7% of national wealth.
This is not evidence that mining alone caused South Africa’s inequality, and it would be intellectually lazy to make that claim. Inequality has many causes, including apartheid dispossession, unemployment, unequal education, land ownership, financialisation, tax policy and weak public institutions.
Mining is at the heart of SA’s economic history
But mining sits at the very heart of South Africa’s economic history, and it has been one of the principal mechanisms through which enormous private fortunes, corporate balance sheets and shareholder wealth were accumulated from finite public resources.
That is why we should be extremely cautious when a period of immense profitability is used to argue that South Africa now needs to unlock even more investment without first asking whether the distributional model itself is working.
We have seen this logic before.
When mining experiences a downturn, the industry tells us that costs must fall, regulation must be reduced, licensing accelerated and investor confidence restored. When profits return, the same profitability becomes evidence that the sector has further growth potential and should be enabled to extract more.
In both circumstances, the policy prescription is remarkably similar: facilitate more investment, improve competitiveness and reduce obstacles to extraction.
What rarely enters the discussion with equal force is whether the distribution of mineral wealth should change.
That omission is especially striking when one looks at the small share of value that has historically been identified as direct community investment. PwC’s earlier value-added statements frequently recorded community investment at only 1% or 2% of value distributed, while shareholder returns were many times higher. In 2022, community investment was reported at 1%, compared with 40% returned to shareholders; in 2023, it was 2%, compared with 37% to shareholders. PwC itself acknowledged that inconsistent reporting made it impossible to construct a robust industry-wide picture of social investment.
Even those figures should be treated cautiously. Mining Affected Communities United in Action’s (Macua) social audits have repeatedly found that up to 70% of the value companies claim to have spent on community projects cannot be independently traced or verified on the ground.
This is where the central contradiction becomes difficult to avoid.
South Africa has extracted extraordinary value from its mineral endowment, yet many of the communities closest to that extraction remain marked by deep poverty, unemployment, polluted land and water, unfinished Social and Labour Plan commitments, inadequate infrastructure and very little ownership of the wealth generated around them.
The problem is therefore not simply that mining has sometimes failed to “trickle down”. The problem is that trickle-down itself has been treated as the model.
Ramaphosa’s inequality committee
That is precisely the kind of structural inequality now being recognised not only by Oxfam, but by the inequality committee President Cyril Ramaphosa himself established during South Africa’s G20 presidency. Led by Nobel laureate Joseph Stiglitz, the committee warned that economic growth and wealth creation do not automatically reduce inequality where ownership, bargaining power and market power remain concentrated. Its analysis goes beyond redistribution after the fact and focuses on what it calls “pre-distribution”: who owns productive assets, who possesses economic power, how the returns to labour and capital are divided and what rules determine who captures the gains from growth. The report therefore calls for deliberate policies to reduce concentrated economic power, strengthen workers’ bargaining power, broaden forms of ownership, rebuild public wealth and use progressive taxation to prevent economic growth from reproducing inequality.
Seen through that lens, the central problem with South Africa’s mining model becomes much clearer. The issue is not that mining has failed to generate wealth. PwC’s own figures show that it has generated extraordinary wealth. The problem is that the institutions governing ownership and distribution have allowed much of that wealth to accumulate elsewhere while mining communities remain poor and largely excluded from ownership of the assets generated from the resources beneath their land.
It is therefore extraordinary that, at precisely the moment when the President’s own G20 committee is warning that concentrated ownership and bargaining power lie at the heart of inequality, South Africa’s mineral-law reform is again being pulled towards the language of investor certainty, competitiveness and accelerated extraction without an equivalent legislative commitment to community ownership, benefit-sharing and economic power.
Implications for mining legislation
The implications for the current mineral-law reform are profound.
The negotiations around the Mineral Resources Development Amendment Bill in the National Economic Development and Labour Council (Nedlac) show business pushing for greater emphasis on investment, growth and making South Africa a globally competitive mining destination, while the community constituency has argued for explicit commitments to substantive equality, community benefit, environmental and gender justice, democratic accountability and meaningful participation in mineral opportunities.
This goes to the heart of whether South Africa intends to use its remaining mineral wealth to reproduce the pattern of the past or to begin changing it.
There is nothing inherently progressive about extracting more minerals if ownership and benefit remain concentrated, communities remain economically marginal and the environmental and social liabilities are left behind.
A larger mining sector operating through the same distributional architecture can simply produce more extraction and more concentrated wealth.
That is why our 100-Year Debt Campaign has asked Parliament for a much broader inquiry into the mining economy.
Reflect both sides of the balance sheet
Our petition does not ask Parliament to begin from the assumption that mining has contributed nothing. Quite the opposite. We want the full account.
Count the taxes and royalties. Count the wages. Count the exports. Count the infrastructure and procurement. Count the almost R1-trillion in cumulative profits reflected in PwC’s historical series. Count the R691-billion in shareholder distributions.
But then complete the balance sheet.
Count the minerals depleted, the jobs lost, the environmental liabilities, the abandoned mines, the Social and Labour Plan promises against what was actually delivered, the public money eventually required to repair damage, and the durable assets and ownership that remain in mining communities after decades of extraction.
Then ask whether South Africa is wealthier in a broad social sense, or merely whether mining companies and asset owners are wealthier.
That is the question Parliament should be asking before it rewrites the law.
Because the most dangerous conclusion to draw from PwC’s extraordinary numbers would be that almost R1-trillion in profit proves we simply need more of the same.
It may prove the opposite.
It may show that South Africa has become extraordinarily effective at producing mineral wealth without distributing it in a way that fundamentally alters the lives of the majority.
And in a country where the richest 1% already owns more than half of all wealth, the answer cannot simply be to accelerate the machinery that has historically concentrated it.
The question is no longer whether mining can generate wealth.
PwC has answered that.
The question is whether South Africa can finally build a mining system in which that wealth is shared differently. DM
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.