Can Hong Kong deliver in trying to build its yuan credentials?
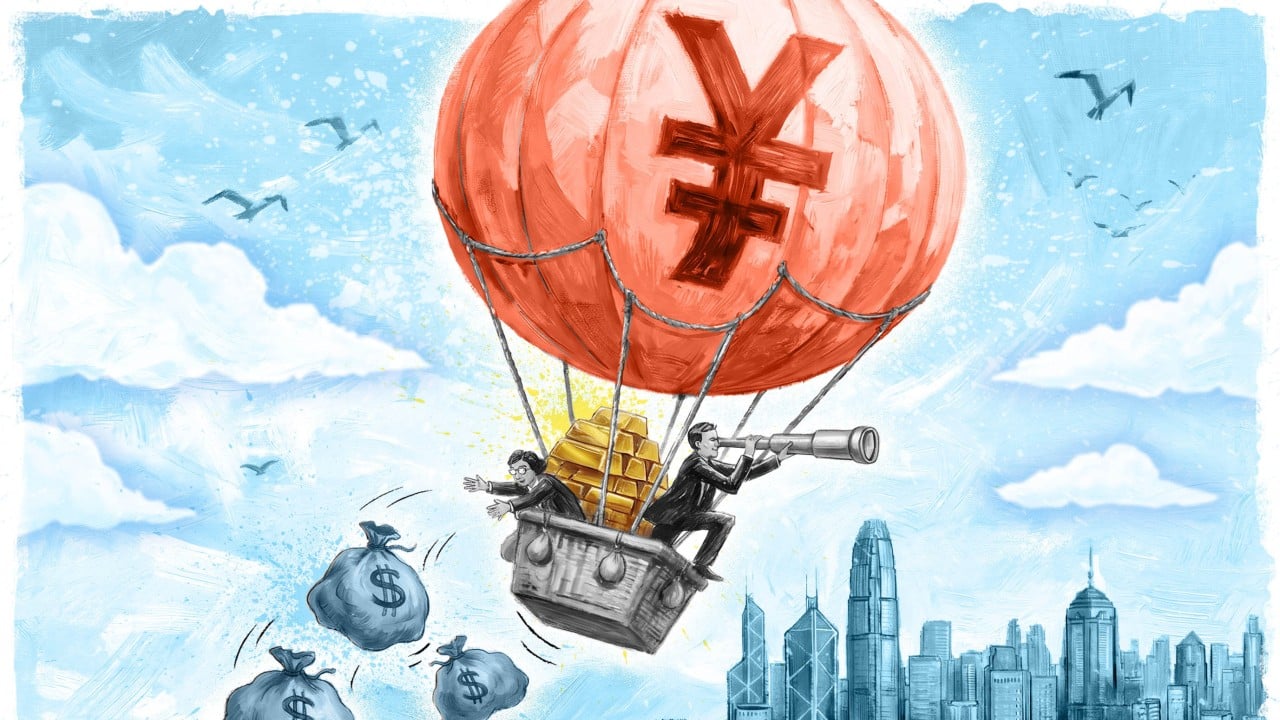
The company, already known for launching the world’s first offshore tokenised yuan money market fund, is not merely pursuing retail investors. It is also at the front line of a coordinated institutional push to build financial protection around Chinese capital against Western market volatility.
The firm’s CEO, Gan Tian, pointed to the recent Middle East crisis as a major “stress test” that demonstrated the Chinese currency’s resilience, noting that the renminbi remained firm even as the US dollar surged and Asian peers like the Japanese yen fell sharply.
“On the path to yuan internationalisation, in this stress test in the first half, the People’s Bank of China has already sent a clear message to the smartest investors in the world,” Gan said.
“If de-dollarisation is a medium- to long-term trend, once you pull your money out of the US dollar, where exactly should you put it? The renminbi is the unparalleled choice.”
Driven by intensifying US-China rivalry and the strategic need to mobilise mainland capital safely abroad despite capital controls, Hong Kong is rapidly transforming its market infrastructure – building a larger offshore renminbi ecosystem, developing independent gold clearing and testing alternative payment channels.
Once primarily a bridge for Western capital entering the mainland, Hong Kong is now positioning itself to support China’s financial resilience, analysts say. The aim, they add, is to establish the city as a launch pad for financial products and payment channels that rely less on traditional Western networks.
Earlier this year, Financial Secretary Paul Chan Mo-po expressed confidence that Hong Kong, currently behind New York and London in the global ranking of international financial centres, would climb to at least second place within 10 to 15 years.
In a recent interview with the South China Morning Post, Chan explained the city’s efforts on yuan internationalisation and their relevance to Hong Kong’s status as an international financial centre.
Chan singled out Hong Kong’s unique role as a firewall for China’s financial security, with yuan-related products and services tested in the city.
“From China’s standpoint, to build a strong country, we need to have a strong currency. But this needs time,” Chan said.
“To strengthen the global utilisation and influence of renminbi, it is the user-case scenario, a substantive business-user case.”
‘Tremendous room for growth’
Chan said he expected global use of the yuan to rise amid geopolitical tensions.
He noted that China accounted for 14 to 15 per cent of global imports and exports combined, but only about 4 per cent of trade was invoiced in yuan last year. The ratio had grown a lot compared with a year earlier, he said.
Foreign investors have shown a strong appetite for trading in mainland stocks through cross-border schemes such as Northbound Stock Connect.
“There is tremendous room for future growth, particularly given the geopolitical context. Most countries are trying to use their own currency in terms of trading,” Chan said.
Hong Kong is the world’s biggest offshore renminbi market, with about 1.3 trillion yuan of deposits as at the end of July, according to the Financial Services and the Treasury Bureau.
A high-profile move to tap international capital took place in August when China’s Ministry of Finance sold 15 billion yuan worth of sovereign bonds in Hong Kong to a strong response from institutional investors.
The sale took place just days after the city launched a long-awaited tool designed to help global investors hedge against risks in the mainland bond market.
Ho Lok-sang, adjunct professor of economics at Lingnan University, said the renminbi remained very much underutilised and did not reflect China’s economic strength, leaving huge potential for wider use.
“What we are after in the long run is that we want to build a more inclusive kind of system,” Ho said.
“At present, the current system, which is very much predominated by the US dollar, is not really an inclusive system, and especially as it has been weaponised.”
US Treasury Secretary Scott Bessent advocated in early September for Washington to use its financial power as a foreign policy tool to advance the interests of American allies, including in financial and political situations abroad.
Meanwhile, the US Treasury Department has warned under its “Operation Economic Outcast” that entities facilitating money laundering or sanctions evasion on behalf of Iran risk being cut off from the US financial system, citing several Hong Kong-based companies that did business with Iran.
“China has been thinking strategically against the possibility that the US might impose different kinds of sanctions, and China is really extremely alert … strategically very, very smart,” Ho said.
Testing ground
Hard data shows the shift away from US dollar-centric systems is well under way in Hong Kong’s capital markets.
Beijing is using Hong Kong to test a China-led multilateral central bank digital currency platform, mBridge, as a potential alternative to the traditional US dollar-dominated payments system. The effort has gained momentum in recent years amid heightened tensions between the world’s two largest economies and growing concerns over the reliability of the US dollar as it becomes politicised.
The project faced a setback late last month after a key participant – the Saudi Central Bank – confirmed its departure after completing what it described as “a limited proof-of-concept” trial in May last year.
Secretary for Financial Services and the Treasury Christopher Hui Ching-yu told the SCMP in an interview earlier this month that the Saudi departure would “not really” affect the wider experiment.
“Fundamentally, what we try to do is, through Hong Kong, at the same time through these measures, to engage different players across the industry in such a way that they can work on some live cases or new cases to test out this technology,” Hui said.
“So technology as it is, people still see the benefit. At the same time, what Hong Kong should do is continue contributing our expertise and also our relevance here.”
Beyond payments infrastructure, Hong Kong is also seeking to make the yuan more attractive for corporate financing.
Multinational firms need to borrow large sums of cash to run their global operations. Historically, many borrowed yen because Japan had the lowest interest rates.
But recently, the script has flipped. Japan’s 10-year sovereign bond yield rose above 3 per cent in early September, while China’s dropped below 1.7 per cent, Gan of ChinaAMC (HK) said.
Global companies were now flocking to Hong Kong to borrow yuan by issuing dim sum bonds – offshore renminbi-denominated bonds – because they offered cheaper funding, Gan said.
He noted that this rush for cheap borrowing had caused the dim sum bond market to explode to 1 trillion yuan, making it significantly larger than Hong Kong’s traditional stock IPO market.
When massive Chinese companies, such as appliance maker Midea, made profits overseas, they faced a huge problem: exchange rates were swinging wildly, Gan said.
Midea suffered a foreign exchange loss of almost 6 billion yuan in six months because the value of the currencies it was holding dropped. Normally, companies buy financial “insurance” with hedging to protect against these US dollar swings, but that insurance can cost 2.5 per cent of the hedged amount every year.
To reduce losses from volatile exchange rates, Chinese companies were simply refusing to convert their cash. Instead, they were parking their overseas profits directly into offshore yuan funds in Hong Kong, Gan said.
Liquidity boost
Chan, the finance chief, has pledged a multipronged strategy to boost yuan liquidity through an array of products. In addition to Chinese treasury bonds, he has pointed to opportunities in stock trading.
He said authorities would consider expanding the number of listed companies whose shares investors could trade using offshore yuan. At present, there are 23 such companies with renminbi business counters.
Chan said another strategy was to allow China-based investors to use renminbi to trade in Hong Kong-listed shares through the Southbound Stock Connect scheme.
“If we can achieve that, the liquidity will be quickly increased,” he said. “In summary, we want to have more product offerings.”
For Hong Kong’s manufacturers and traders, the stakes extend beyond financial markets.
Anthony Lam Sai-ho, chairman of the Federation of Hong Kong Industries, said that pricing commodities in renminbi would link finance more directly with physical supply chains, giving manufacturers a “natural hedge” against exchange rate volatility.
“If we can trade commodities in renminbi … it provides manufacturers and stakeholders with an additional method to hedge and predict procurement costs, reducing currency fluctuation,” Lam said.
He added that while markets were accustomed to US dollar pricing, importing raw materials such as rice or base metals directly in local currencies or renminbi would reduce the risk of being caught between shifting exchange rates.
“It is less about avoiding the US dollar out of fear, and more about giving the market an additional option to balance trade,” Lam added.
Commodity trading had so far started with gold but could extend to other metals, energy, grains, soft commodities and even livestock, Lam said.
Alternative clearing networks, meanwhile, are expanding their reach. China’s Cross-border Interbank Payment System (CIPS) processed 180 trillion yuan in cross-border payments in 2025, up 373.6 times the 2015 level, according to its website.
CIPS said it provided secure, efficient, convenient and low-cost cross-border renminbi payment and settlement services for global users, offering an additional channel beyond the US-dominated financial system.
That existing US dollar-based system relies heavily on Swift, the Belgium-based Society for Worldwide Interbank Financial Telecommunication, which connects more than 12,500 institutions across more than 220 countries and territories and enables global trade.
Dollar payments are also settled through the Clearing House Interbank Payments System (Chips), a private-sector, high-value clearing and settlement system that helps financial institutions move domestic and cross-border wire payments, according to its website.
Under Chief Executive John Lee Ka-chiu’s policy address in September, the government has established the Hong Kong Precious Metals Central Clearing Company and will implement targeted measures to boost the trading and settlement of gold futures contracts using the offshore renminbi.
Kenny Shui Chi-wai, vice-president of think tank Our Hong Kong Foundation, said market participants would have another option if access to dollar-based channels were restricted.
“A gold clearing system allows gold transactions via a local central ledger without relying on the Swift messaging network or the Chips payment system, thereby providing an alternative store of value,” Shui said.
“Unlike fiat currencies, gold is a physical commodity that inherently holds value, making it a trusted safe asset not directly tied to any jurisdiction.”
Gan of ChinaAMC (HK) said that having huge physical gold reserves in Hong Kong provided foreigners using offshore renminbi in the city with a “Plan B” if they wanted to convert or transfer those funds.
“They do not need to convert their assets into US dollars, British pounds or Japanese yen to move them globally; they can directly exchange them for physical gold in Hong Kong and have it delivered anywhere in the world,” he said.
“Therefore, gold, acting as a ‘Plan B’ and the most important collateral asset of the future, will support the development of the offshore renminbi in Hong Kong.”
The peg question
The Hong Kong Securities and Futures Professionals Association warned that an overnight shift away from the US dollar was unrealistic.
“If de-dollarisation is overemphasised, international investors might interpret it as a signal of declining openness,” said the association’s chairman, Mofiz Chan.
Chan said Hong Kong had to strike a delicate balance between securing multiple sources of capital and maintaining its international free-market reputation with compliance, transparency and neutral standing.
To make this “financial armour” truly functional, the association called for specific technological and regulatory upgrades.
Gregory Yu, head of markets at Hong Kong Exchanges and Clearing, told the SCMP that the exchange was focused on building a more comprehensive offshore renminbi ecosystem spanning equities, fixed income, currencies and commodities, and it was actively exploring opportunities to expand the range of yuan-denominated products.
“Initiatives including the continued expansion of the LME’s warehouse network in Hong Kong strengthen the market infrastructure that supports trading, storage and delivery activities across the region,” Yu said, referring to the London Metal Exchange.
Yu added that the bourse continued to explore opportunities to enhance market efficiency through innovation, including in digital assets and tokenisation.
“Together with ongoing market infrastructure enhancements, these efforts strengthen Hong Kong’s role as the world’s leading offshore renminbi hub and reinforce its position as an international financial centre connecting China and the world,” Yu said.
But any push to reduce reliance on the US dollar runs up against a basic constraint: the Hong Kong dollar remains pegged to it.
Ho Lok-sang argued that linking exclusively to the US dollar exposed Hong Kong to extreme economic swings, recalling the 1985 “super dollar” phase, when the city lost its export competitiveness.
“It’s much, much, much better if we can peg a basket of currencies … and now devise a way to seamlessly adopt the system without any shock at all,” Ho said.
“We can continue with the linked exchange rate system, but we just link with the basket,” he added, referring to a GDP-weighted basket that would include the renminbi, euro, yen, British pound and the US, Australian and Canadian dollars.
Chan, the finance chief, along with city leader John Lee Ka-chiu have said repeatedly the government has no intention of changing the 43-year-old peg, which has been underpinning the city’s economy.
At the end of the day, the key buzzwords are hedging and strategic planning, analysts say.
And the official regulatory response has been to rapidly deepen the multi-asset ecosystem and expand mutual market access to facilitate this capital transition.
“For Hong Kong, this means strengthening its role as a resilient international financial centre while supporting the financing of Chinese technology companies and renminbi internationalisation,” Shui of the think tank said.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.