Insurance regulator sets 5 flood-damage levels for vehicles
Completely submerged vehicles may be considered total losses, depending on policy terms
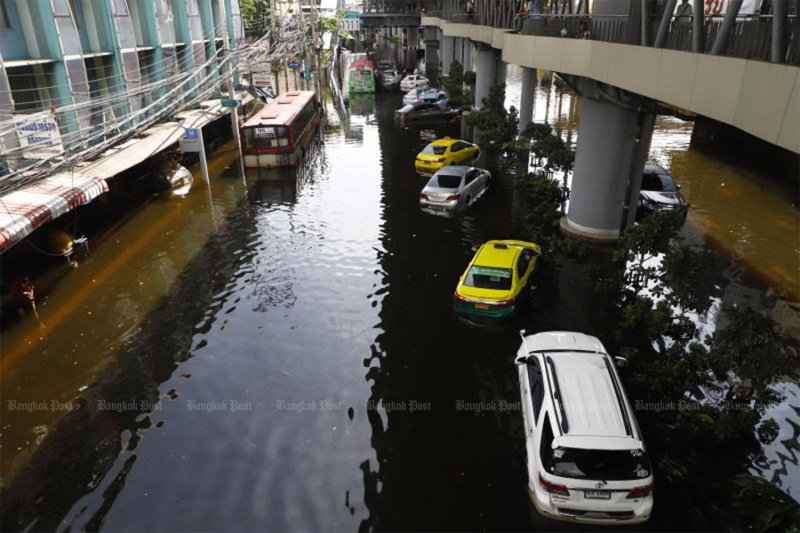
The Office of Insurance Commission (OIC) has set five damage levels for flood-affected combustion-engine vehicles, based on how high the water reaches, as Thai insurers prepare for a surge in claims once floodwaters recede.
The five levels are:
- Level A: Water reaches the floor carpet; estimated repair costs are 8,000 to 10,000 baht.
- Level B: Water reaches the seats; estimated repairs cost 15,000 to 20,000 baht.
- Level C: Water reaches the lower dashboard; estimated repair costs are 25,000 to 30,000 baht.
- Level D: Water reaches the upper dashboard; repair costs exceed 30,000 baht.
- Level E: The vehicle is completely submerged and may be deemed a total loss, subject to the terms of the insurance policy.
For electric vehicles (EVs), assessments must also consider battery and other vehicle damage, along with the requirements of the relevant manufacturer and model.
OIC secretary-general Chuchatr Pramoolpol urged flood victims to put safety first and avoid returning to flooded or unsafe areas to collect evidence for insurance claims. If an area remains inaccessible, policyholders should notify their insurers and gather further evidence when it is safe to do so.
For flooded vehicles, policyholders should check whether their policies cover flood damage. Type 1 motor insurance includes flood coverage, while Type 2+ and Type 3+ policyholders should check whether they have purchased additional flood coverage.
The OIC warned motorists not to start flooded vehicles, as doing so could cause further damage to the engine, electrical systems and interior equipment. Once it is safe, owners should photograph or record the vehicle’s exterior and interior, including water levels or watermarks. They should then notify their insurers, providing their policy details, registration number, location and details of the damage.
The OIC has instructed insurers to ensure they have enough staff, loss adjusters, claims channels, repair shops, tow trucks and other resources to handle a potential rise in claims. Insurers must also speed up damage surveys and enter inaccessible areas as soon as conditions allow.
For homes and other property, policyholders should check whether their policies cover natural disasters or flooding and review the applicable coverage limits. Once it is safe, they should document damage to structures, floors, walls, furniture and electrical appliances, including water levels or watermarks. They should also prepare a list of damaged items before notifying their insurers.
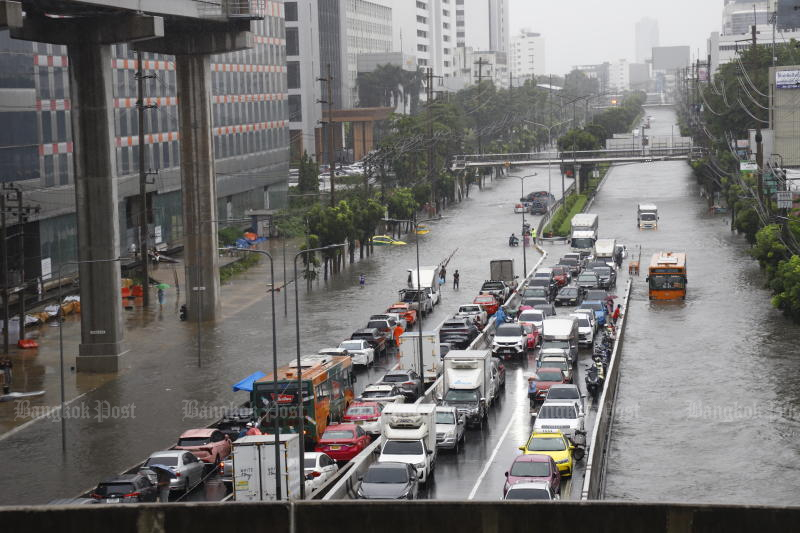
The scene on Lat Phrao Road following continuous heavy rainfall, which has triggered widespread flash flooding, on Sept 26, 2026. Floodwaters have inundated the roadway, forcing cars, public buses and motorcycles to navigate the deep waters with difficulty. (Photo: Nutthawat Wichieanbut)
The OIC has instructed insurers to assess claims promptly. When damage is clearly established, claims should be paid within seven days. For total-loss cases, relevant documents should be collected alongside the damage assessment. The agency will coordinate with relevant agencies to help reduce documentation and settlement delays for vehicles under hire-purchase agreements.
The regulator has created a central directory of insurers’ claims channels on its website and LINE Official Account, @OICCONNECT. Policyholders can also use these channels to check policy information and seek insurance advice.
The OIC hotline, 1186, will be available 24 hours a day through Oct 5 for inquiries, complaints and assistance. Policyholders can also use the OIC’s online channels and PPMS complaint system.
Mr Chuchatr said policyholders should not worry if they are unable to collect all documents or evidence during the flooding. They should notify their insurers first and gather any additional evidence once conditions are safe, he added.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.