IMF urges members to stock up funds to aid poor states
The US and other wealthy nations need to urgently tackle mounting global debt levels that are weighing most heavily on low-income countries and straining the global financial system, IMF managing director Kristalina Georgieva said yesterday.
US Secretary of the Treasury Scott Bessent and other US leaders recognize that the federal deficit and national debt are too high, but economic growth alone would not be enough to address the country’s more than US$40 trillion in national debt, Georgieva said.
Meanwhile, rising bond yields, reflecting higher premiums demanded by investors for taking on greater risk, have been disrupting financial markets, she said.
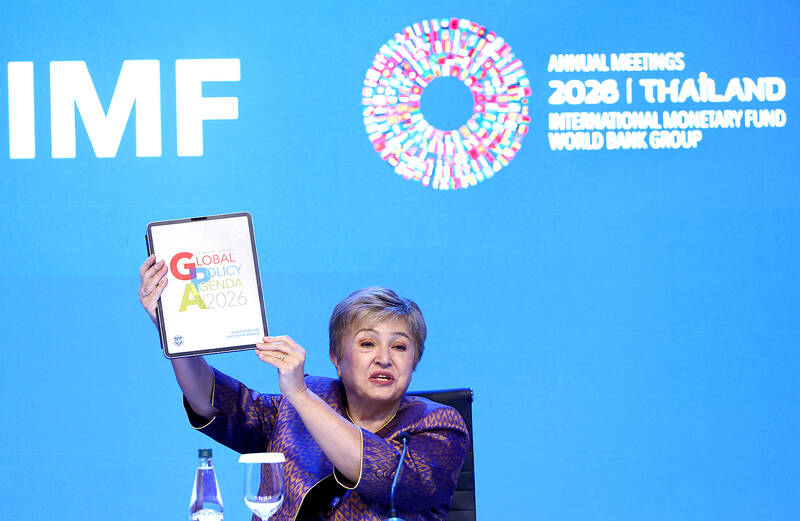
IMF managing director Kristalina Georgieva speaks at an event in Bangkok yesterday.
Photo: EPA
“We believe that growth, of course, helps, but it cannot deliver fast enough the necessary adjustments,” Georgieva said at the autumn meeting of the IMF and the World Bank in Bangkok.
“There is no magic,” she said, adding that other measures would be needed.
“You have to go in a direction of tightening, bringing it down, bringing the deficit down,” she said.
Rising debt levels and global inflation have pushed interest rates to multidecade highs, adding to the burdens of the world’s poorest nations.
Efforts to bring debt under control with what Georgieva and other experts call “fiscal consolidation” have suffered setbacks from heavy spending during the COVID-19 pandemic and since.
“Fiscal risks are rising and a proper reaction is largely absent in many countries,” said Rodrigo Valdes, director of the IMF’s Fiscal Affairs Department.
“And in major advanced economies, the effect of fiscal indiscipline does not stop at the border. It travels to the rest of the world,” Valdes added.
“Among the world’s poorest countries, interest payments have reached historic highs relative to revenue, and declining amounts of aid are creating gaps that some countries have been unable to finance,” the IMF’s latest Fiscal Monitor said.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.