Diwali Fireworks Gone Wrong? 3 Insurance Policies That Can Save You
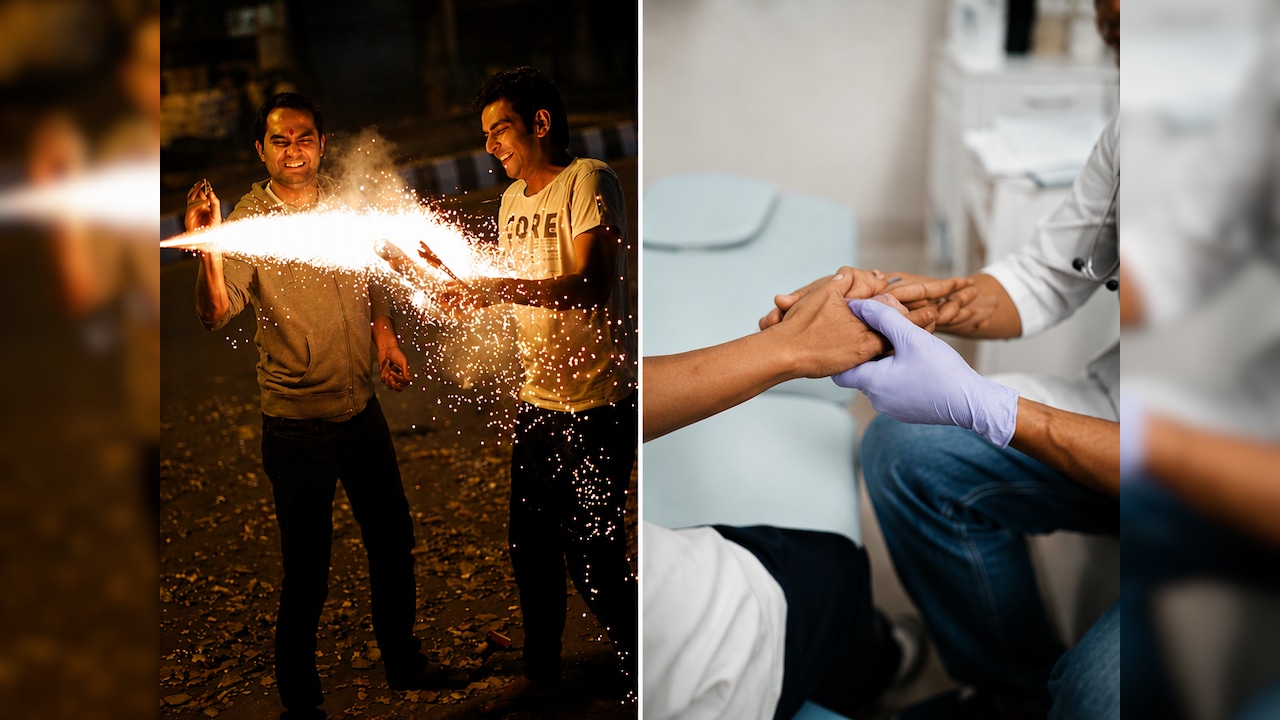
Diwali is a time for celebrations, sweets and fireworks. But sometimes, a few seconds of excitement can turn into a medical emergency. A stray rocket can cause serious burns, a spark can damage a car, or a firecracker can trigger a fire in a neighbouring house. Beyond the physical damage, such accidents can leave families struggling with unexpected medical bills and property losses.
But does your insurance cover accidents caused by firecrackers during Diwali?
While many people look for special firecracker insurance policies around the festival, financial protection does not necessarily require a separate Diwali-specific cover. Existing health, personal accident and home insurance policies may already offer protection, depending on their terms and conditions.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Rakesh Goyal, Director of Probus, told NDTV that people should first understand the protection offered by their existing insurance policies instead of rushing to buy a seasonal cover. "Diwali-related accidents can have serious financial consequences, particularly when they involve hospitalisation, permanent disability or damage to property. People should review their existing insurance policies and understand what is covered, rather than assuming that every firecracker-related incident will automatically qualify for a claim," said Goyal.
1. Health Insurance: Who Pays For Firecracker Injuries?
Burn injuries, eye damage and other accidents caused by firecrackers can require immediate medical attention. In serious cases, patients may need surgery, intensive care and prolonged hospitalisation. This is where health insurance becomes important.
A standard health insurance policy generally covers medically necessary hospitalisation arising from accidental injuries, subject to its terms, exclusions and coverage limits. This could include hospital room charges, surgery, medicines and doctors' fees.
However, not every medical expense is necessarily covered. If the injury requires only a routine outpatient consultation or dressing, the patient may have to pay from their own pocket unless the policy includes OPD benefits. People should also check their sum insured, waiting periods and other policy conditions before assuming that all expenses will be reimbursed.
2. Personal Accident Insurance: Protection Beyond Hospital Bills
Health insurance can take care of eligible medical expenses. But what happens if a firecracker accident leaves someone permanently disabled or results in death?
This is where personal accident insurance can provide an additional layer of financial protection. Unlike health insurance, which primarily covers medical expenses, personal accident insurance provides benefits for specified accidental outcomes. Depending on the policy, these may include accidental death, permanent total disability and permanent partial disability.
The payout can help the affected family manage everyday expenses, repay loans and deal with the loss of income. Goyal points out that families should not look at insurance only as a way to pay hospital bills. "An accident can affect a family's finances long after the medical treatment is over. A personal accident policy can provide a lump-sum benefit in cases of covered disability or accidental death. This financial support can be particularly important for families that depend on a single earning member," he said.
3. Home Insurance: What If A Firecracker Sets Your House On Fire?
Firecracker accidents are not limited to physical injuries. A stray rocket or a falling spark can start a fire, damaging balconies, windows, furniture and electrical equipment. In such situations, health insurance will offer no protection. Home insurance becomes relevant.
A home insurance policy covering the building can protect against specified fire-related damage to the insured structure. Depending on the policy, contents insurance can also cover household belongings such as furniture, appliances and other valuables.
Chetan Vasudeva, Senior Vice President - Business Development at Elephant.in, Alliance Insurance Brokers, told NDTV that fire damage caused by crackers or fireworks is generally insurable under an all-risk policy, provided fire is an insured peril and the incident does not fall under any exclusion.
According to Vasudeva, the bigger concern for homeowners is whether their policy covers only the building or its contents as well. "Most policyholders usually have the building covered but do not take the cost of furniture, electronic devices, jewellery and artworks into consideration when taking out their insurance policies," he explains.
This can become a costly oversight. Even if the building is insured, expensive household belongings may not be adequately protected. Vasudeva says high-value assets may need to be specifically declared under the policy. Depending on the product, insurers may also ask for invoices and other documents establishing ownership.
Homeowners should therefore check whether their policy covers the building, household contents or both. They should also verify the insured value of their belongings rather than assuming that everything inside the house is automatically covered.
When Can An Insurance Company Reject Your Claim?
Buying insurance does not mean every firecracker-related accident will automatically qualify for compensation. Insurance companies assess claims based on policy conditions, exclusions and the circumstances surrounding the incident.
For instance, injuries or damage arising from illegal activities, deliberate acts or violations of applicable laws may attract exclusions. Claims involving banned or prohibited fireworks could also face scrutiny, depending on the circumstances and policy wording.
Vasudeva highlights that home insurance policies also contain conditions relating to deliberate damage. Damage resulting from a wilful act may not be covered. Some products may also exclude losses arising from electrical or mechanical breakdowns.
Similarly, if someone suffers an asthma attack because of worsening air pollution during Diwali, the claim would be assessed under the health insurance policy's medical coverage, waiting periods and exclusions. It would not automatically qualify as a firecracker accident claim.
Goyal says policyholders should pay attention to the fine print instead of judging an insurance product only by its premium. "Insurance is meant to provide financial support during unforeseen situations, but the coverage is always subject to policy terms and conditions. People should understand exclusions, claim limits and the nature of protection available to them. A low premium does not necessarily mean adequate protection," he said.
Fire At Home? Here's What You Should Do Before Filing A Claim
Knowing that your home is insured is only half the job. How you respond after a fire can also matter when filing an insurance claim.
Vasudeva advises policyholders to prioritise safety during a fire-related incident. Once the situation is under control, they should inform the insurance company immediately instead of waiting until all documents and arrangements are in place.
Photographs of the damage, fire brigade reports, police reports wherever required, purchase invoices, valuation reports and repair estimates can help support the claim.
There is another important precaution. Homeowners should avoid repairing or throwing away damaged belongings before the insurer or its appointed surveyor has inspected the property.
However, if emergency repairs or removal of damaged items are necessary for safety reasons, the policyholder should document the situation properly through photographs and other available records. This can help establish the extent of the damage and avoid complications during claim assessment.
What Should You Check Before Diwali?
Before the festivities begin, a quick review of your insurance portfolio can help avoid unpleasant surprises later.
Here are five things worth checking:
- Health insurance: Check your sum insured, hospitalisation coverage and whether accidental injuries are covered.
- Personal accident cover: Understand the benefits available for accidental death and permanent disability.
- Home insurance: Verify whether the building and household contents are insured against fire damage.
- Policy exclusions: Read the conditions relating to negligence, deliberate acts and prohibited fireworks.
- Claim procedure: Keep your insurer's helpline number and policy documents handy. Understand the claim intimation process and preserve relevant evidence in case of an accident.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.