OPEN SECRETS: PetroSA’s rehabilitation fund shortfall is a ticking timebomb
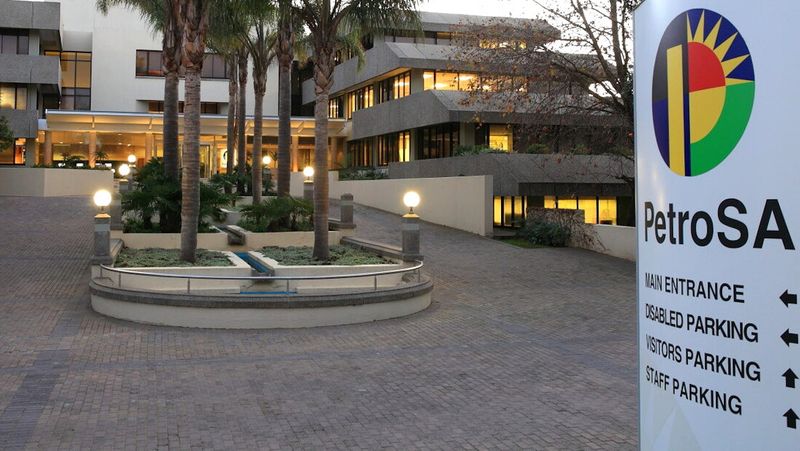
In 2021, the CEO of the Central Energy Fund (CEF), Dr Ishmael Poolo, called PetroSA’s decommissioning liability – the money required to safely decommission its onshore and offshore oil and gas operations – a “monster”. He added that attempts to repurpose PetroSA’s oil infrastructure at the time was in part to delay that liability from coming due.
Five years on, the liability problem hasn’t gone anywhere, but there has been no urgency on the part of PetroSA, the CEF nor the Ministry of Mineral and Petroleum Resources to address the problem. Instead, a new South African National Petroleum Corporation (SANPC) has been launched to much fanfare. The SANPC incorporates large parts of PetroSA but the decommissioning liability has been conveniently excluded as a “legacy” issue. At the same time, updated financial regulations meant to ensure that these kinds of decommissioning liabilities are properly addressed have been repeatedly delayed.
The result is an unfunded multibillion-rand decommissioning liability with no apparent plan to address it. This raises serious concerns about the environmental risks posed by PetroSA’s offshore and onshore operations – most of which are defunct or mothballed – that are legally required to be safely decommissioned. It also means that there is a real risk that the financial cost will fall to the fiscus, and thus to all of us.
Just how big is the monster?
A decommissioning liability is often reduced to a number in a financial report, but it’s worth remembering that it’s a vital part of protecting our constitutional rights to a safe environment. South African law requires applicants for environmental authorisation and holders of rights to prospecting, mining, exploration, production or related activities to make financial provision for rehabilitation, mitigation of environmental damage, decommissioning and closure and post-closure management of the sites where they operate.
Put simply, a holder of a right to undertake extractive activities is required to estimate what it will cost to fully rehabilitate its operations, address any environmental damage and safely close the site. It then must come up with the money and ensure it has the financial means to fulfil those obligations.
PetroSA has long faced a massive shortfall in its financial provision for rehabilitation and decommissioning. In 2020, the last time PetroSA published an integrated annual report, it included a report from the Auditor-General that estimated PetroSA’s full rehabilitation obligations to be R12.4-billion. At the time it only had R2.8-billion in cash ringfenced for this – a R9.6-billion shortfall.
Very little progress has been made to close this gap since. According to the 2025 integrated annual report of the Central Energy Fund (CEF) – PetroSA’s holding company – PetroSA’s rehabilitation obligations are now estimated at R10.1-billion and make up almost all the CEF’s rehabilitation obligations, which total R11-billion. The report indicates that PetroSA still only has R3.1-billion in “rehabilitation ringfenced funds”, though it elsewhere claims that PetroSA has R3.5-billion “set aside” in a dedicated entity – the PetroSA Rehabilitation Company. The shortfall thus sits between R6.6-billion and R7-billion.
It seems strange that the rehabilitation obligation estimate has come down so significantly from 2020 to 2025 – falling from R12.4-billion to just R10.1-billion. However, this may be due to certain assets being excluded from the most recent estimate. The CEF report indicates that global firm Det Norske Veritas (DNV) Pty Ltd (DNV) – headquartered in Oslo – was commissioned by PetroSA in 2025 to come up with the estimate, but it also notes that PetroSA had not included its “plugged and abandoned legacy wells” from the provisioning. It is not clear why this exclusion is justified.
Regardless of the true extent of the shortfall, the multibillion liability is a key reason that PetroSA has long been technically insolvent and unable to obtain finance from financial institutions.
The SANPC’s PetroSA conundrum
The unfunded liability also posed a problem to the formation of the new state-owned oil company – the SANPC. In April 2024, the then minister of mineral resources and energy, Gwede Mantashe, announced the appointment of the board and executive team of the new entity. The board would have been intimately familiar with PetroSA’s money troubles; since it included three former senior PetroSA executives including two former Group CEOs.
The SANPC has commenced operations but will remain an interim subsidiary of the CEF until the National Petroleum Bill is promulgated into law. Until then, the company operates under a lease and assign model whereby certain assets of the merging entities are leased to the SANPC.
The SANPC will work across the oil and gas value chain and was supposed to be a full merger of the South African Gas Development Company (iGas), Strategic Fuel Fund and PetroSA. But PetroSA’s rehabilitation liability reared its head again. It meant that it was financially unviable to incorporate PetroSA in its entirety and was viewed as a significant financial risk for the new company to secure financing.
The state’s solution was to simply carve up the entity. Only the Trading Supply and Logistics division of PetroSA was deemed financially viable to be merged into the new company. This is the division that has long kept PetroSA on life support, by controversially sourcing and selling diesel to Eskom at incredibly high prices.
PetroSA’s legacy assets, including the decommissioning liability, have instead been ringfenced and described as “legacy assets requiring further work to be done before they could be transferred into the SANPC”. As noted in a submission to Parliament on the SANPC Bill by civil society group Green Connection, the effect of this is to effectively sever PetroSA’s liabilities from the assets that exist to fund them. The likely result, and one we have seen elsewhere in the mining sector, is that the liability will fall to the state and the public.
The only other plan that PetroSA had to start generating revenue to cover the shortfall was to restart its Mossel Bay gas-to-liquids refinery. This plan has also been mired in controversy after PetroSA controversially opted to partner with Gazprombank to restart the refinery, a partnership that failed and was cancelled in 2025. Months later, the South African Revenue Service took steps to attach the refinery over PetroSA’s R4.5-billion tax debt.
As time passes, it seems increasingly unlikely that PetroSA will be able to generate revenue or secure financing that would address its massive liabilities. Worryingly, the SANPC Bill also appears to be unclear on what will ultimately happen to these liabilities. In its parliamentary submission, Green Connection notes that one section of the Bill refers to the assets and rights of PetroSA and other entities and makes no reference to liabilities. However, another section states that all assets, rights, liabilities and obligations of PetroSA and the other entities would pass to the SANPC when the Act comes into effect.
South Africa’s extractive industries rehabilitation problem
The ongoing failure of PetroSA to make financial provisioning for rehabilitation is symptomatic of South Africa’s failed regulation system, in terms of its ability to hold corporations accountable for their environmental impact, especially those in the minerals-energy complex. The immediate consequences of failure to make financial provisioning for rehabilitation is the environmental harm experienced by communities living next to extractive industries.
In May 2026, the Centre for Environmental Rights (CER) released a report titled No More Ghost Towns: Lessons from Mpumalanga’s Mine Closure Crisis. It highlights the devastating environmental, economic and social impacts of abandoned mines in Mpumalanga. It says rehabilitation rarely takes place, and that inadequate financial provisioning has often left the financial burden to fall to the state instead of the corporation that should hold the responsibility.
A case study in the report focuses on Ermelo, a mining town in Mpumalanga, where residents continue to face polluted land and water systems after mines were shut down or abandoned without proper mitigation and rehabilitation. In one instance, the abandoned Imbabala mine has left open pits that have killed children and livestock, and contaminated water in the area. Yet, despite repeated appeals to the state to remedy the situation, the site has still not been properly closed or rehabilitated 15 years after it was abandoned.
These risks are heightened when the company involved enters liquidation without adequate funds being put aside for rehabilitation. This is not an academic concern for PetroSA. In September, one of its suppliers approached the high court seeking PetroSA’s liquidation over a R600-million bill it has not, and apparently cannot, pay. The supplier – Nako Energy – has a history of dubious and costly diesel contracts with PetroSA.
Given the environmentally sensitive nature of PetroSA’s oil and gas operations, both onshore and offshore, these are some of the enormous possible risks that await if the status quo remains. Unfortunately, as is the case in the coal mining sector, neither PetroSA nor the state seems to be moving to mitigate the crisis.
Legal progress meets corporate lobbying
Another key factor in the delays in addressing PetroSA’s unfunded liability for decommissioning is the continuous delays in the process to ensure that up-to-date regulations in terms of South Africa’s National Environmental Management Act (Nema) apply to PetroSA.
In 2015, new financial provisioning regulations were passed in terms of Nema that introduced new and more effective – if still imperfect – rules to ensure that companies set aside adequate funds for rehabilitation. The changes were a response to some of the significant limitations in the previous legal framework that had led to so many failures to ensure effective rehabilitation and sought to introduce better practice.
Yet, one of the major gaps in these new regulations is that they apply differently to any holder of a right that was granted prior to November 2015, including PetroSA. Instead of the requirements for new rights holders, a transitional provision ensures that holders of older rights remain bound by older versions of legislation that is repealed. Responding to questions about this, the Department of Forestry, Fisheries and the Environment (DFFE) insisted that this was not a regulatory gap, and that it fell to the minister of mineral and petroleum resources to enforce these provisions, especially given PetroSA’s shortfall.
We sent detailed questions to the minister, Mantashe, but received no reply.
The transitional arrangements were supposed to be addressed quickly. Initially, older rights holders were required to align their financial provision with the 2015 regulations by 20 February 2017. However, litigation by major companies – including DRDGold Limited and Sibanye Gold Limited – challenged this deadline and it was subsequently extended to 20 February 2019. Since then, the deadline has been repeatedly extended and delayed, against the warnings of civil society groups.
Responding to questions about these delays, the DFFE said that the number of substantive comments received drew out the process, and the required collaboration with other national departments further delayed the process.
Right now, there is no set date for when older rights holders will be fully bound by the up-to-date regulations. The DFFE told Open Secrets that it expects the latest version of the amendments to be published for comment this month, for implementation by the end of March 2027. Yet, regulations have been regularly published for comment without being finalised. As noted by CER, this not only creates serious regulatory uncertainty, but halts one important step to ensure that financial provisioning for rehabilitation is improved across the extractives sector.
Conclusion
South Africa’s regulatory framework has continuously failed the public when it comes to ensuring that extractive corporations fulfil their legal obligations to rehabilitate the environments in which they operate. Time and again, local communities face the immediate environmental and social consequences, while the costs fall to the public.
Having kicked the can down the road for decades, and with PetroSA now facing liquidation, this risk is present again. At a minimum, the fiscus may need to provide R7-billion for PetroSA’s closure and decommissioning, though the cost might be far higher. It is one more indictment of the many failures of leadership of PetroSA and the Department of Mineral and Petroleum Resources over decades. Sadly, it is again the public that will pick up the tab. DM
The Department of Mineral and Petroleum Resources, the Central Energy Fund and PetroSA were contacted for comment. None replied, but the article will be updated should any further comment be received.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.