Buy A Shop, Earn Rent, Retire Early? We Did The Math Behind The Dream
For many Indians, owning a shop is more than a real estate investment. It is a retirement plan. Buy a small commercial property, rent it out and collect money every month. Over time, the property could rise in value, the rent could increase and the owner could eventually retire without depending entirely on a pension or savings.
The idea sounds simple. But there is a catch. Buying a shop can require a large upfront investment, and the rent may not be enough to cover the loan EMI. The owner may have to put money into the property for years before it starts generating a meaningful surplus.
So, can one shop really help fund your retirement?
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Stage 1: Buying The First Shop
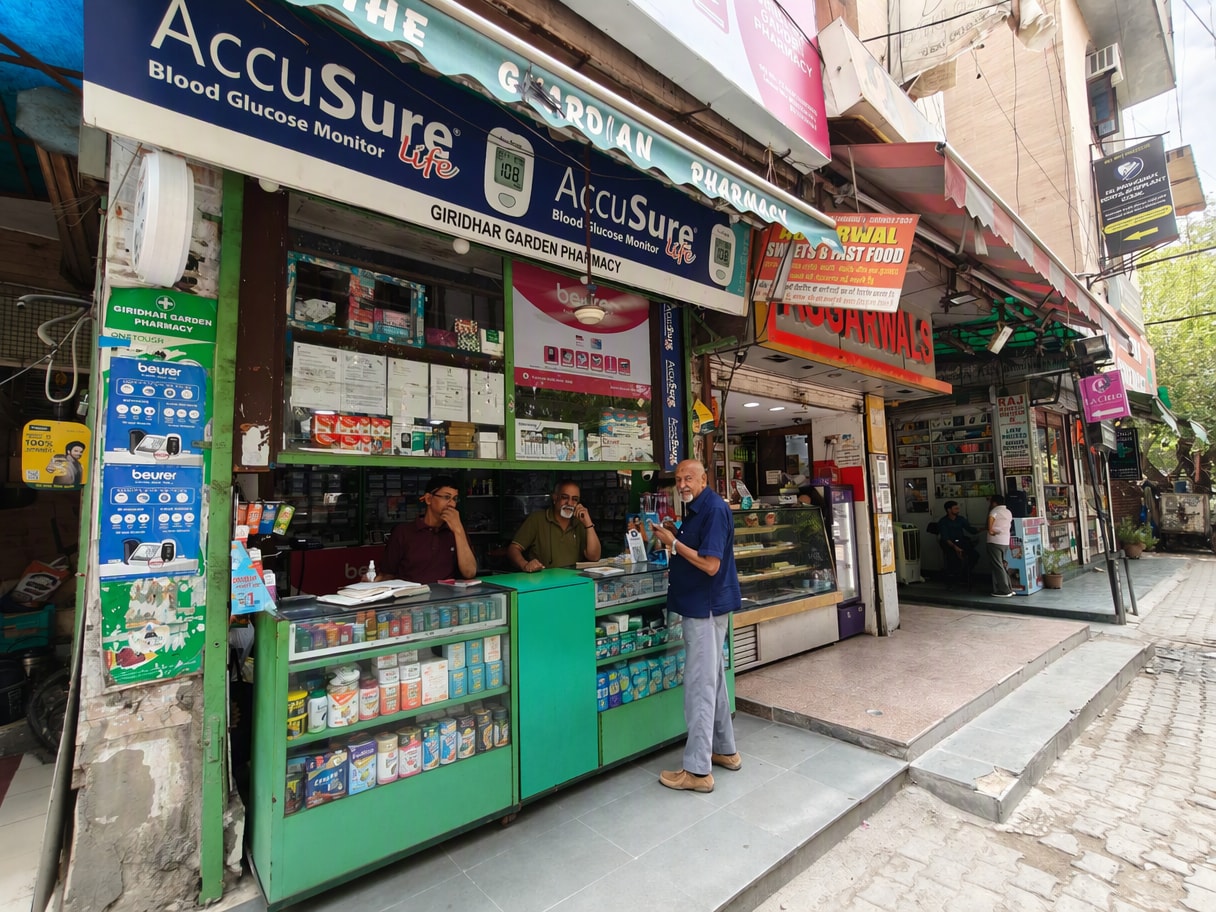
Let's assume an investor buys a commercial shop for Rs 50 lakh and rents it out for Rs 25,000 a month. That brings in Rs 3 lakh a year. On paper, the property offers a gross rental yield of 6 per cent. Rental yield is the annual rent expressed as a percentage of the property's purchase price.
But the rent quoted by a broker is not the money the owner gets to keep. Commercial properties need regular maintenance. There may be repairs, property-related expenses and periods when the shop remains vacant. For this calculation, let's set aside 15 per cent of the rent for these costs.
That leaves Rs 2.55 lakh a year, or Rs 21,250 a month, before loan repayments and income tax. The property's net operating yield works out to 5.1 per cent.
Now consider how the investor finances the purchase. Suppose they make a down payment of Rs 10 lakh and borrow the remaining Rs 40 lakh for 20 years at an assumed interest rate of 9 per cent. The monthly EMI would be around Rs 36,000.
The problem is immediately clear. The shop generates about Rs 21,250 a month after the assumed operating costs, but the EMI is around Rs 36,000. The investor must make up the difference from their salary, savings or another source of income. The monthly shortfall is approximately Rs 14,750, even before income tax.
There is also the cost of stamp duty, registration and other purchase-related charges to consider. These would increase the initial investment. The shop, therefore, is not yet funding the investor's retirement. The investor is funding the shop.
However, that does not automatically make the purchase a bad investment. Part of every EMI goes towards repaying the loan, helping the owner build equity in the property. The shop may also appreciate over time. But neither appreciation nor future rental income is guaranteed.
Atul Monga, CEO and Co-founder of BASIC Home Loan, told NDTV that commercial property can play a role in long-term financial security when investors understand the income it can generate and the costs involved. The first lesson is straightforward: do not judge a shop by its monthly rent alone. Calculate what remains after expenses and compare it with the EMI.
Stage 2: The 15-Year Wait
The next part of the plan depends on patience. The investor continues to hold the property, pays the EMIs and hopes that both its value and rental income grow over time. Let's assume the shop's value rises by 5 per cent annually. Its rent also increases by 5 per cent every year. These are illustrative assumptions, not a prediction of how any particular property will perform.
After 15 years, the shop's estimated value would rise from Rs 50 lakh to around Rs 1.04 crore. The monthly rent could increase from Rs 25,000 to approximately Rs 52,000. That translates into annual rental income of about Rs 6.24 lakh.
If the owner continues to set aside 15 per cent for operating costs and vacancies, the remaining amount would be around Rs 5.30 lakh a year, or Rs 44,200 a month. This is before income tax and any outstanding loan repayments.
The difference is significant. The property could be worth more than twice its original purchase price, while its rent could also have doubled. However, the actual outcome will depend on the location, demand for commercial space, the property's condition and the quality of its tenants. A shop in a busy commercial corridor may perform very differently from one in a poorly occupied retail complex.
Shiv Garg, Director of Forteasia Realty, points to rental demand as one reason investors consider commercial property for income generation. "Strong growth has made the potential for passive income from real estate more attractive than equities. There is positive and consistent demand for rentals in both residential and commercial real estate. Depending on the micro market, yields are around 3-7% each year. These have assisted in boosting real estate as a stable and income generating asset that is well insulated against inflation," Garg told NDTV.
The next decision is whether to keep the original shop or sell it and buy a larger property. Selling could release capital for an upgrade to an established business district, a prime high street or a well-connected commercial corridor. A more expensive property may generate higher rent, but it will also require more capital.
The investor must account for the outstanding loan, selling expenses, applicable taxes and the cost of buying the replacement property. The amount left over may be considerably lower than the sale price.
There is another important distinction. A property worth Rs 1 crore does not automatically generate enough rent to fund retirement. Its income potential depends on the rental yield and the costs of ownership, not just its market value.
Trading up can be an option, but it is not a guaranteed shortcut to a larger rental income.
Stage 3: Can The Shop Fund Retirement?
The real benefit of the investment may emerge when the owner retires and the loan has been fully repaid.
Without an EMI, a much larger share of the rental income can be used to meet everyday expenses. The owner could use the money to supplement a pension, pay household bills or reduce withdrawals from other investments.
But how much income would the investor actually need?
Suppose the goal is to earn Rs 50,000 a month from the property in today's money. That amounts to Rs 6 lakh a year.
The first shop generates illustrative net operating income of Rs 2.55 lakh a year. That covers around 43 per cent of the target, before financing and income tax.
After 15 years, the projected net operating income rises to about Rs 5.30 lakh a year. That is much closer to the target in future rupees.
But there is a catch. Rs 50,000 received 15 years from now will not buy as much as Rs 50,000 does today. Inflation will push up the amount needed to maintain the same lifestyle.
The investor must also consider how much money is tied up in the property. A shop may be valuable, but it cannot always be sold quickly without accepting a lower price. An investor who depends entirely on rental income could also face financial pressure if the tenant leaves or the property needs major repairs.
This is why retirement planning must begin with an income target, rather than the value the investor hopes the property will reach.
Stage 4: Keep The Rent Or Run Your Own Business?
Retirement does not necessarily mean the owner must stop working altogether. A debt-free commercial property offers another option: running a business from the premises.
The owner could open a store, a service outlet or another business suited to the location. Since there would be no rent payable to an outside landlord, the business would avoid that particular expense.
But owning the premises does not guarantee that the business will succeed. The owner would still have to invest in inventory, staff, equipment and day-to-day operations. Running a business also requires time and effort.
The alternative is to lease the property to a tenant and collect rent. This may involve less daily work, although the owner would still need to manage vacancies, repairs, tenant agreements and other responsibilities.
Vijay Raundal, Managing Director of Teerth Realties, emphasises the importance of building assets for the long term. "We believe in building long lasting assets, not just structures. Grade-A commercial developments meet modern corporate requirements through better design, safety, efficiency and comfort. They also provide stability and better returns for investors, making them a sustainable choice for all stakeholders," Raundal told NDTV.
A commercial property can also become part of a family's financial legacy. The owner may eventually pass it on to their children, who could continue collecting rent or use the premises for a business of their own.
That, however, does not make the asset entirely maintenance-free. The next generation would inherit both its income potential and its responsibilities.
Can One Shop Really Help You Retire Early?
The answer depends on the purchase price, the rent, the loan, the property's location and how much income the owner needs after retirement. A shop bought with a large loan may put pressure on household finances for years. A property purchased at a reasonable price, in a location with sustainable rental demand, could gradually become a source of income as the loan is repaid.
Before making the investment, there are three numbers worth examining closely.
First, the net rental yield. The headline rent is only the starting point. Account for maintenance, repairs, vacancies and other operating expenses to estimate the income the property can actually generate.
Second, the retirement-income gap. Work out how much monthly income you will need and how much of it the property could realistically provide. Remember that inflation will increase your future expenses.
Third, the total cost of ownership. Include the down payment, loan repayments, purchase charges and the money you may need to spend when the shop is vacant or requires repairs. Also consider whether you can manage the investment without dipping into money meant for emergencies.
There is one final point. A commercial property is a concentrated investment. Much of the owner's wealth may depend on one location, one tenant and one local market. Keeping other savings and investments can help reduce that dependence.
The dream of buying a shop and retiring on rent is not unrealistic. But it is neither effortless nor guaranteed.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.