Banks are responding to improved monetary policy conditions – John Awuah
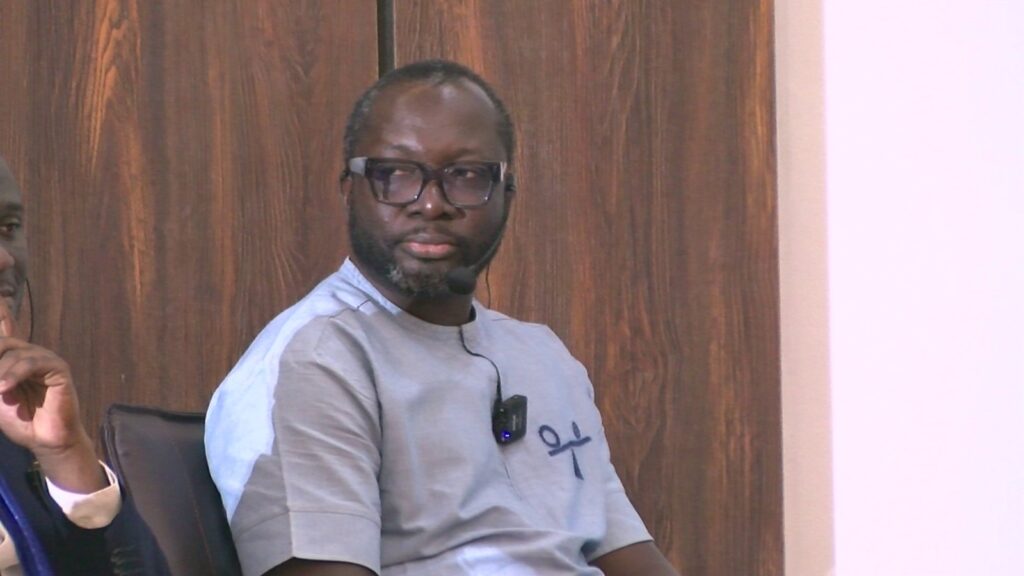
The Chief Executive Officer of the Ghana Association of Banks, John Awuah, has defended the banking sector’s lending practices, arguing that a decline in borrowing costs and strong private sector credit growth demonstrate that banks are responding to improving monetary conditions.
He said the Bank of Ghana’s decision to maintain the monetary policy rate at 14 % was a strategic move to observe the impact of global happenings on the banking sector.
Speaking at a post-Monetary Policy Committee (MPC) policy discussion organised by Chartered Institute of Bankers Ghana, Mr Awuah cited data from the Bank of Ghana’s latest MPC release, which indicates that private sector credit grew by 29 per cent year-on-year in real terms.
“Contrary to perhaps public view that banks are not lending, banks are interested in this or that, there is actually evidence on the ground to suggest that banks are lending,” he said.
Mr Awuah noted that although the central bank has maintained its benchmark rate at 14 % since March, commercial lending rates have continued to ease.
“Between March and September, the policy rate has been kept at 14 %. But I can tell you between March and September, bank lending rate has continued to decline from upwards of 18% somewhere in March to around where we are now, where we’re talking about 15.9,” he said.
He explained that the average lending rate of 15.9 % includes pricing for some legacy exposures, while new loans are attracting rates ranging between 9 and 12 %.
“If you are taking real exposures on the books, new exposures, you are talking about between nine and 12 %,” he stated, describing the decline as significant compared with lending conditions a year to 18 months earlier.
The figures, he argued, demonstrate that changes in the broader economic environment and monetary conditions can influence lending costs even when the policy rate remains unchanged.
Despite the improvement in lending rates, Mr Awuah warned that Ghana’s high non-performing loan (NPL) ratio remains a major obstacle to expanding affordable credit. He put the sector’s NPL ratio at approximately 15.8 %, contrasting it with figures he cited for Côte d’Ivoire, Nigeria and Togo.
“The non-performing loan ratio in Togo is under 10 %. The non-performing loan in Côte d’Ivoire is under 7 %. The non-performing loan in Nigeria is under 9 %, and Ghana, we are clapping at 15.8%” he said.
To illustrate the impact on banks, he added “For every 100 cedis of your money that we give out, we are likely going to lose 16 cedis. That is how, if you express it in cedis, it tells the story better.”
According to him, the cost of defaults affects banks’ willingness and capacity to extend credit, ultimately influencing the interest rates charged to borrowers.
He therefore urged policymakers and stakeholders to look beyond comparisons of lending rates across countries and address the underlying factors that make credit more expensive in Ghana.
He argued that although the Borrowers and Lenders Act provides a framework for collateral enforcement, legal challenges can delay the recovery process and increase the risks associated with lending.
“What do we see? A bank uses the Borrowers and Lenders Act, notifies the collateral registry, notifies the court that this customer has met all the conditions for recovery and therefore the underlying asset is going to be disposed of. What do we see? They run to the court,” he said.
He maintained that efficient enforcement of credit agreements is necessary to protect the banking system and ensure that funds can be made available to other borrowers.
“Why it is important to do that is so that the next borrower does not suffer, so that the bank is enabled to be able to give funding to the next borrower,” he explained.
Mr Awuah further called for stronger collaboration among institutions involved in the business environment, including regulatory agencies, to address structural inefficiencies that affect borrowers’ ability to operate and repay loans.
Mr Awuah rejected suggestions that banks are reluctant to lend, insisting that financial intermediation remains central to their operations. He added that banks would be willing to extend credit at more competitive rates if the risks associated with lending were reduced.
“Our job is to financially intermediate. The day we fail at that job, we don’t have banks, but we need the system to facilitate that. Tomorrow, a bank will pick up the phone and tell you, ‘Ellen, there’s a funding for you. We’ve looked at your credit history. We think you deserve one million Ghana cedis at 5 per cent.’ And then you come for it. That is why we exist. Banks do not shy away from lending because that is a piece of cake.” he said.
His remarks highlight the relationship between monetary policy, lending rates and credit availability, suggesting that sustained reductions in borrowing costs will depend not only on the central bank’s policy decisions but also on improvements in loan recovery, credit risk management and the wider business environment.
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
Tags:
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.