Expert explains why you shouldn’t get annoyed about state pension changes
A finance expert has urged people to take control and responsibility of their retirement in the wake of incoming changes to the state pension, reminding savers: “The state pension is the floor, not the roof.”
Andy Burnham announced that the triple lock will be replaced from its current form by 2030 onwards, to bring down the ballooning cost of funding it. The changes are expected to save between £5bn and £20bn a year over the long term, with money put towards funding a new social care service.
While the move has been deemed necessary by several economic experts due to the fast-rising state pension cost, it naturally drew criticism from some parties worried that they would have less money in future to support themselves.
But that, says Gina Miller, founder of women-focused investment platform MoneyShe, misses the point of both people having the opportunity to improve their own retirement fund, as well as the social construct that the state pension is formed around.
“I think of retirement as a house,” Ms Miller said. “The state pension is the floor: solid, protected against inflation and essential. But a floor is not a shelter. Your workplace pension builds the walls, and your own savings are the roof.
“The government owns the floor, and it has just announced how it will maintain it. The walls and the roof are yours.”
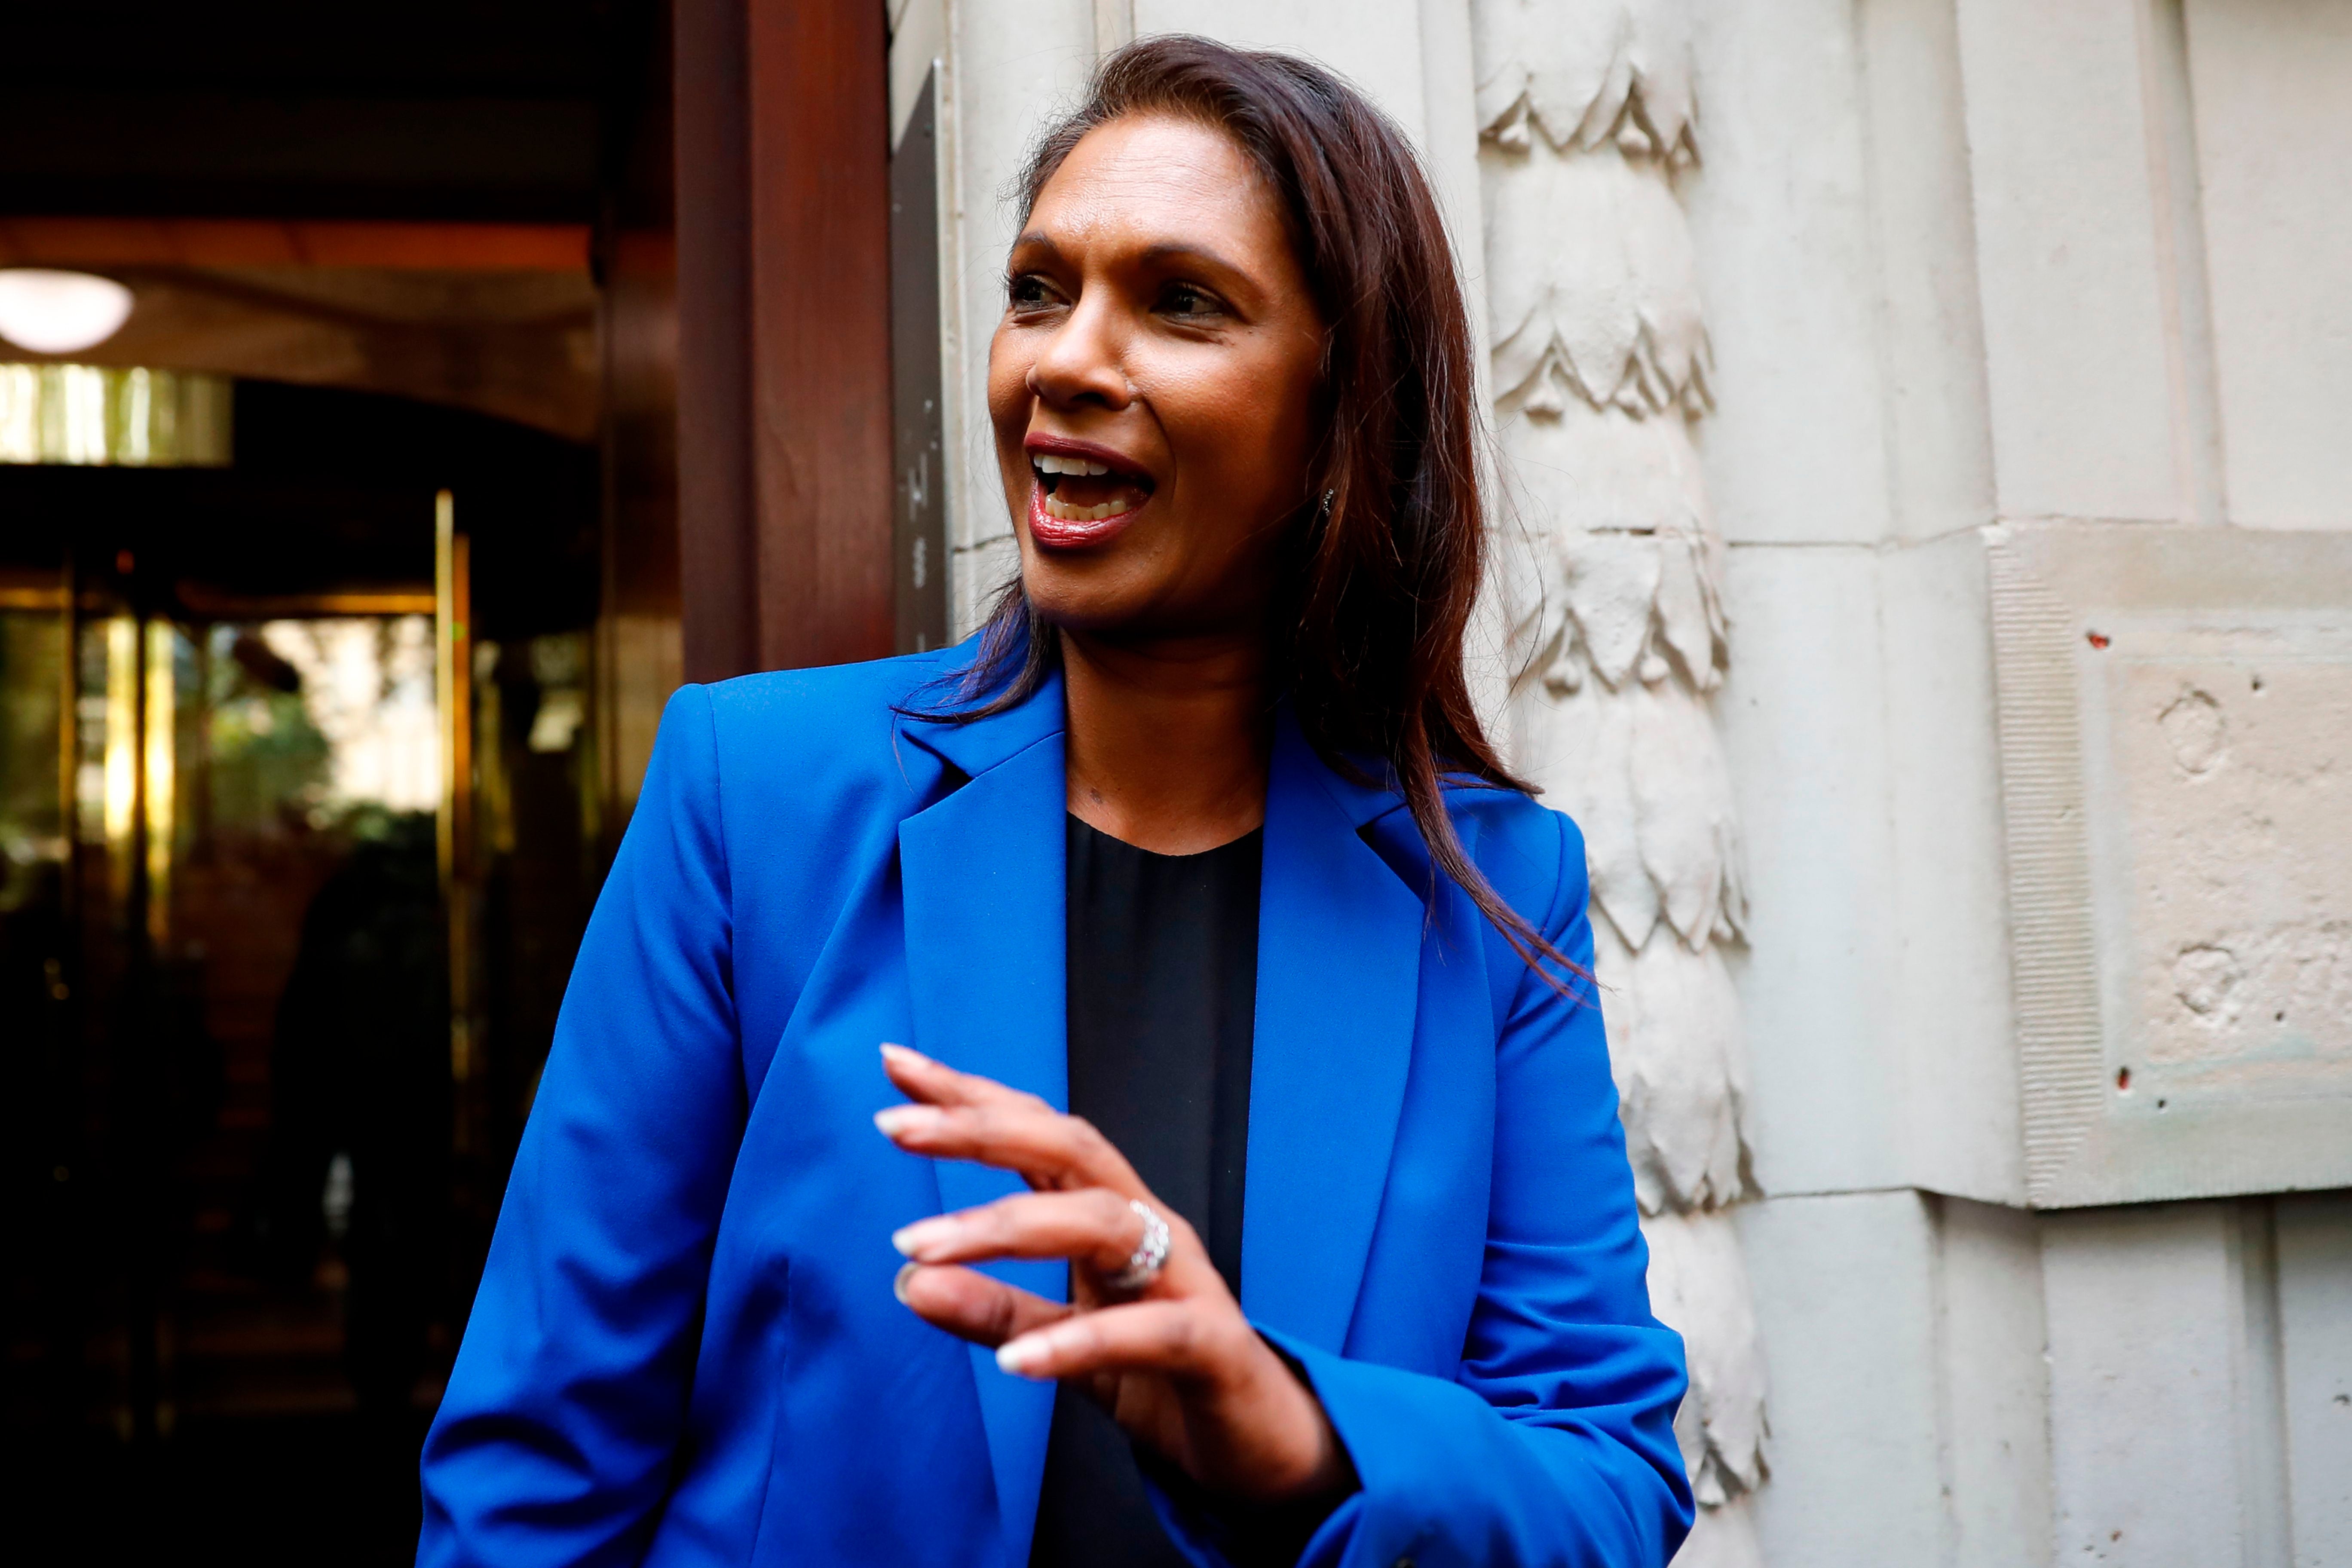
As for how the state pension works, Ms Miller, a campaigner who famously took the government to court over Brexit, noted that it’s not about workers getting back less than they paid into the service.
“Most people don’t realise that their National Insurance isn’t being saved for them. It pays today’s pensioners and buys a promise that depends on the workers who come after us. That is why this reform matters, and why no one should treat the state pension as their whole retirement plan,” she added.

Invest at least £100 in Stocks or ETFs of your choice. Get fractional shares worth £50!
Terms and conditions apply.
Go to websiteADVERTISEMENT
Invest at least £100 in Stocks or ETFs of your choice. Get fractional shares worth £50!
Terms and conditions apply.
Go to websiteADVERTISEMENT
A full state pension is set to grow by £500 next year, in line with wage growth from 2026. But in future calculations, the wage growth figure will be taken as an average from 2030 onwards, rather than individual yearly elevations. That, along with 2.5 per cent or the rate of inflation, will determine how much the state pension grows the following year.
But, as Ms Miller notes, the state pension is intended as a starting point for retirement savings, not the full amount of financial support – though inevitably it may remain the case for some people.
Building retirement savings through personal or workplace pensions, or long-term investments, should also factor in peoples’ retirement goals, particularly as small contributions over long periods in these products can benefit from compounding.
However, Ms Miller further notes that for women, a retirement savings gap still exists and more needs to be done to close that due to the impacts of different life moments.
The recent comprehensive Great British Retirement Survey for 2026 by interactive investor highlighted as much, with results showing the average defined contribution (DC) pension pot is worth £45,000 for women - but £175,000 for men.
In addition, more than a third (37 per cent) of women are living on a personal income below £15,000 in retirement, compared to fewer than two in ten (18 per cent) men.
“A steadier, more predictable state pension is a welcome step. But it will still be modest, and career breaks, caring and part-time work mean women are far more likely to have gaps in both their state and private pensions,” Ms Miller continued.
“I urge women to check their state pension forecast this week. It takes minutes, and it’s the first step to building the rest of their retirement shelter.”
The Independent recently reported that seven million UK adults have never checked their state pension forecast, which can give an overview of how close or on track each person is to getting a full amount.
Along with checking state pension forecasts, Ms Miller recommends people fill in gaps in NI records with credits or voluntary contributions - which can ensure you get a bigger, or full, state pension when you hit retirement age - and review workplace pension contributions, particularly if your employer has an employee match scheme on offer.
Building long-term savings and working backwards from the retirement you want, to working out the amount you need to save yourself, are also important steps.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.