Northrop Grumman beats estimates as defense backlog reaches $110B
MikeMareen/iStock via Getty Images
Northrop Grumman (NOC) reported better-than-expected third-quarter earnings Tuesday as higher sales of military aircraft and defense systems helped lift revenue and push its order backlog to a record $110 billion. The company also raised its full-year profit outlook.
Shares of Northrop Grumman (NOC) were little changed in premarket trading Tuesday. The stock had fallen 10% for the year through Monday's closing price, compared with a 12% gain for the S&P 500 index.
The Falls Church, Virginia-based defense contractor reported third-quarter revenue of $11.12 billion, up 7% from $10.42 billion a year earlier. Revenue fell approximately $30 million short of Wall Street's consensus estimate of $11.15 billion.
Earnings increased to $7.89 a share from $7.67 a year earlier, beating analysts' consensus estimate of $7.20 a share by 69 cents. The reported earnings figure is based on generally accepted accounting principles rather than a separately disclosed quarterly adjusted earnings measure.
Net income rose to $1.12 billion, or $7.89 a share, from $1.10 billion, or $7.67 a share, a year earlier.
The results highlight the contrast between strong demand for Northrop Grumman's (NOC) defense technology and its stock market performance this year. Military spending on advanced aircraft, missile systems and strategic deterrence programs has supported new contract awards, but investors remain concerned about profitability and execution risks on large, technically demanding programs. The company's growing backlog provides substantial revenue visibility, although converting those orders into profitable sales will depend on production efficiency, contract performance and government funding.
Defense orders push backlog to record levels
Northrop Grumman (NOC) received $16.4 billion in net contract awards during the quarter, producing a book-to-bill ratio of approximately 1.5. The measure indicates that new orders substantially exceeded revenue recognized during the period.
Total backlog reached $109.6 billion at the end of September, up 15% from $95.7 billion at the end of 2025.
"In a complex world with the growing need for solutions that scale and perform, our customers continue to turn to Northrop Grumman," Chair, Chief Executive and President Kathy Warden said in the earnings announcement.
Major third-quarter awards included $4.6 billion for classified programs, $2 billion for the Sentinel intercontinental ballistic missile program and $1.4 billion for Virginia-class submarines.
The company also received $1.3 billion in awards related to the F-35 fighter jet and $1 billion for the E-2 Hawkeye airborne early warning aircraft.
Defense Systems accounted for the largest portion of the company's backlog at $36.5 billion, followed by Aeronautics Systems at $26.8 billion and Space Systems at $26.3 billion.
B-21 bomber and F-35 programs
Aeronautics Systems reported third-quarter revenue of $3.58 billion, up 14% from $3.14 billion a year earlier.
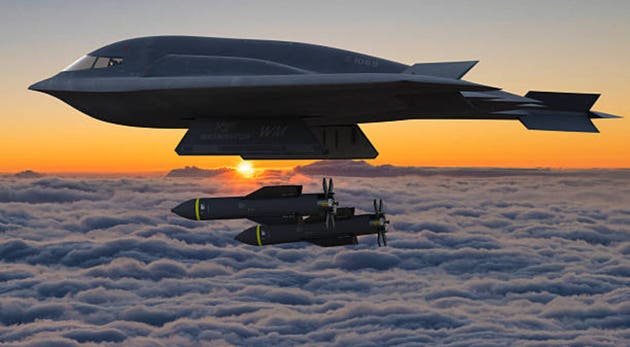
Growth reflected higher sales on the F-35 fighter program, increased activity involving the B-21 Raider stealth bomber and additional maintenance and support work on the B-2 bomber.
Operating income at Aeronautics Systems increased 24% to $377 million, while its operating margin improved to 10.5% from 9.7%.
Defense Systems revenue rose 12% to $2.31 billion, supported by increased activity on the Sentinel missile program, the Extended Range Guided Multiple Launch Rocket System and tactical solid rocket motors.
However, Defense Systems operating income increased just 7% to $250 million. Its operating margin declined to 10.8% from 11.4%, reflecting a shift toward contracts with lower profit margins.
The Sentinel program remains particularly important to the company's long-term outlook because of its role in modernizing the U.S. nuclear deterrent. Higher activity is supporting revenue growth, although the program's scale and complexity create execution risks.
Space, electronics businesses post modest growth
Mission Systems reported revenue of $3.16 billion, up 2% from a year earlier. Higher activity on classified airborne radar and marine systems programs was partially offset by lower sales in advanced microelectronics.
Operating income at Mission Systems declined 3% to $500 million, with its operating margin falling to 15.8% from 16.7%.
Space Systems revenue increased 2% to $2.75 billion, driven by growth in classified space programs. The increase was partially offset by $136 million in lower sales from commercial resupply missions because of launch timing.
Operating income at Space Systems rose 5% to $312 million, while its operating margin improved to 11.3% from 11%.
Across the company, segment operating income increased 5% to $1.35 billion. However, the segment operating margin declined to 12.1% from 12.3%, underscoring the challenge of translating higher sales into stronger profitability.
Raises 2026 earnings forecast
Northrop Grumman (NOC) raised its full-year 2026 forecast for mark-to-market-adjusted earnings to $29.35 to $29.75 a share, up from its previous range of $28.60 to $29.10.
The revised earnings outlook is above the supplied Wall Street consensus estimate of $24.98 a share. The company's mark-to-market-adjusted earnings measure excludes certain pension-related valuation effects.
Management maintained its annual sales forecast of $43.75 billion to $44.25 billion. The midpoint of $44 billion is slightly below analysts' consensus estimate of $44.05 billion.
The company also increased its forecast for full-year segment operating income to $4.94 billion to $5.04 billion, compared with its previous range of $4.85 billion to $5 billion.
Adjusted free cash flow is expected to total $3.1 billion to $3.5 billion for the year.
The higher profit forecast reflects management's expectations for improved operating performance during the remainder of 2026, despite relatively modest growth in some business segments.
Cash flow improves as investors assess execution risks
Northrop Grumman (NOC) reported third-quarter operating cash flow of $1.75 billion, up 12% from $1.56 billion a year earlier.
Adjusted free cash flow increased 44% to $1.81 billion from $1.26 billion. The latest figure included $371 million in proceeds from the sale of equipment to a customer.
For the first nine months of 2026, adjusted free cash flow totaled $965 million, compared with $72 million during the corresponding period last year.
The company's third-quarter operating margin declined to 11.4% from 11.9%, despite higher revenue. Management attributed the decrease primarily to a less favorable pension accounting adjustment.
Net earnings benefited from a lower effective income tax rate of 13.4%, compared with 16.9% a year earlier, largely because of higher research tax credits.
For investors, the central question is whether Northrop Grumman (NOC) can turn its expanding backlog into sustained earnings and cash flow growth. Demand for its aircraft, missile and space technologies remains strong, but its stock's underperformance relative to the broader market suggests investors are still looking for evidence of more consistent profitability and program execution.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.