Motilal Oswal Sees 40% Upside In This Rooftop Solar Stock: Should You Buy?
Share Market News: India's rooftop solar boom is creating opportunities for companies that can make more than just solar panels. One such company is Fujiyama Power Systems, which sells solar inverters, batteries and other products under the UTL Solar brand.
The company has delivered strong growth in the September quarter. Its revenue more than doubled, while net profit also surged over 100 per cent. It is now expanding manufacturing capacity across solar cells, lithium-ion batteries and power electronics to capture a larger share of India's growing rooftop solar market.
The performance has caught the attention of domestic brokerage Motilal Oswal, which has maintained its 'Buy' rating on the stock and sees an upside of around 40 per cent from current levels.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
But is the stock worth considering after its sharp growth? And what should investors watch before making a decision?
Fujiyama Power Systems Q2 Results: Revenue More Than Doubles
Fujiyama Power Systems reported revenue from operations of Rs 13,068 million in Q2 FY27, compared with Rs 5,679 million in the corresponding quarter last year. This translates into a growth of 130.1 per cent.
EBITDA increased 116.4 per cent to Rs 2,229 million from Rs 1,030 million. Profit after tax (PAT) rose 111.2 per cent to Rs 1,329 million against Rs 629 million a year ago.
However, the company saw some pressure on profitability. Its EBITDA margin declined to 17.1 per cent from 18.1 per cent in the year-ago quarter. PAT margin also fell to 10.2 per cent from 11.1 per cent.
The sequential performance was less impressive. Revenue declined 2.9 per cent from Rs 13,457 million in Q1 FY27, while EBITDA fell 12.5 per cent to Rs 2,229 million.
Bawal Plant Fire: The One-Off Hit To Profit
In May 2026, a fire damaged Fujiyama's tubular battery manufacturing plant in Bawal, Haryana. The facility had a capacity of 1.3 GWh.
The company subsequently made a provision of Rs 1,436 million towards the loss. After accounting for tax, the impact on profit stood at Rs 1,074 million.
This affected its reported Q1 FY27 profit. Excluding the one-time impact, the company's normalised PAT for Q1 stood at Rs 1,652 million.
Against this adjusted figure, Q2 FY27 normalised PAT of Rs 1,329 million represents a sequential decline of 19.6 per cent. There could, however, be some relief on the cash flow front. Fujiyama has filed an insurance claim for the full carrying value of the damaged assets. Management expects the claim to be resolved and the money to be realised during FY27.
Despite the fire-related provision, Fujiyama's first-half performance remained robust. Revenue for H1 FY27 increased 127.6 per cent to Rs 26,525 million from Rs 11,653 million in the corresponding period last year.
EBITDA jumped 128.7 per cent to Rs 4,777 million. The EBITDA margin remained broadly stable at 18 per cent against 17.9 per cent a year ago. Normalised PAT increased 128.4 per cent to Rs 2,981 million from Rs 1,305 million.
However, reported PAT stood at Rs 1,907 million, up 46.1 per cent, largely due to the provision made following the Bawal plant fire.
Motilal Oswal Sees Strong Growth Ahead
Motilal Oswal described Fujiyama's Q2 performance as a strong beat against its estimates.
Revenue came in at Rs 13.1 billion against the brokerage's estimate of Rs 10 billion. EBITDA stood at Rs 2.2 billion compared with an estimate of Rs 1.9 billion. Adjusted PAT of Rs 1.3 billion also exceeded its estimate of Rs 1.1 billion.
The only disappointment was the EBITDA margin, which came in at 17.1 per cent against the brokerage's expectation of 19 per cent.
The brokerage has maintained its 'Buy' rating and a target price of Rs 500. Against the reference market price of Rs 357 in its report, this indicates an upside potential of approximately 40 per cent.
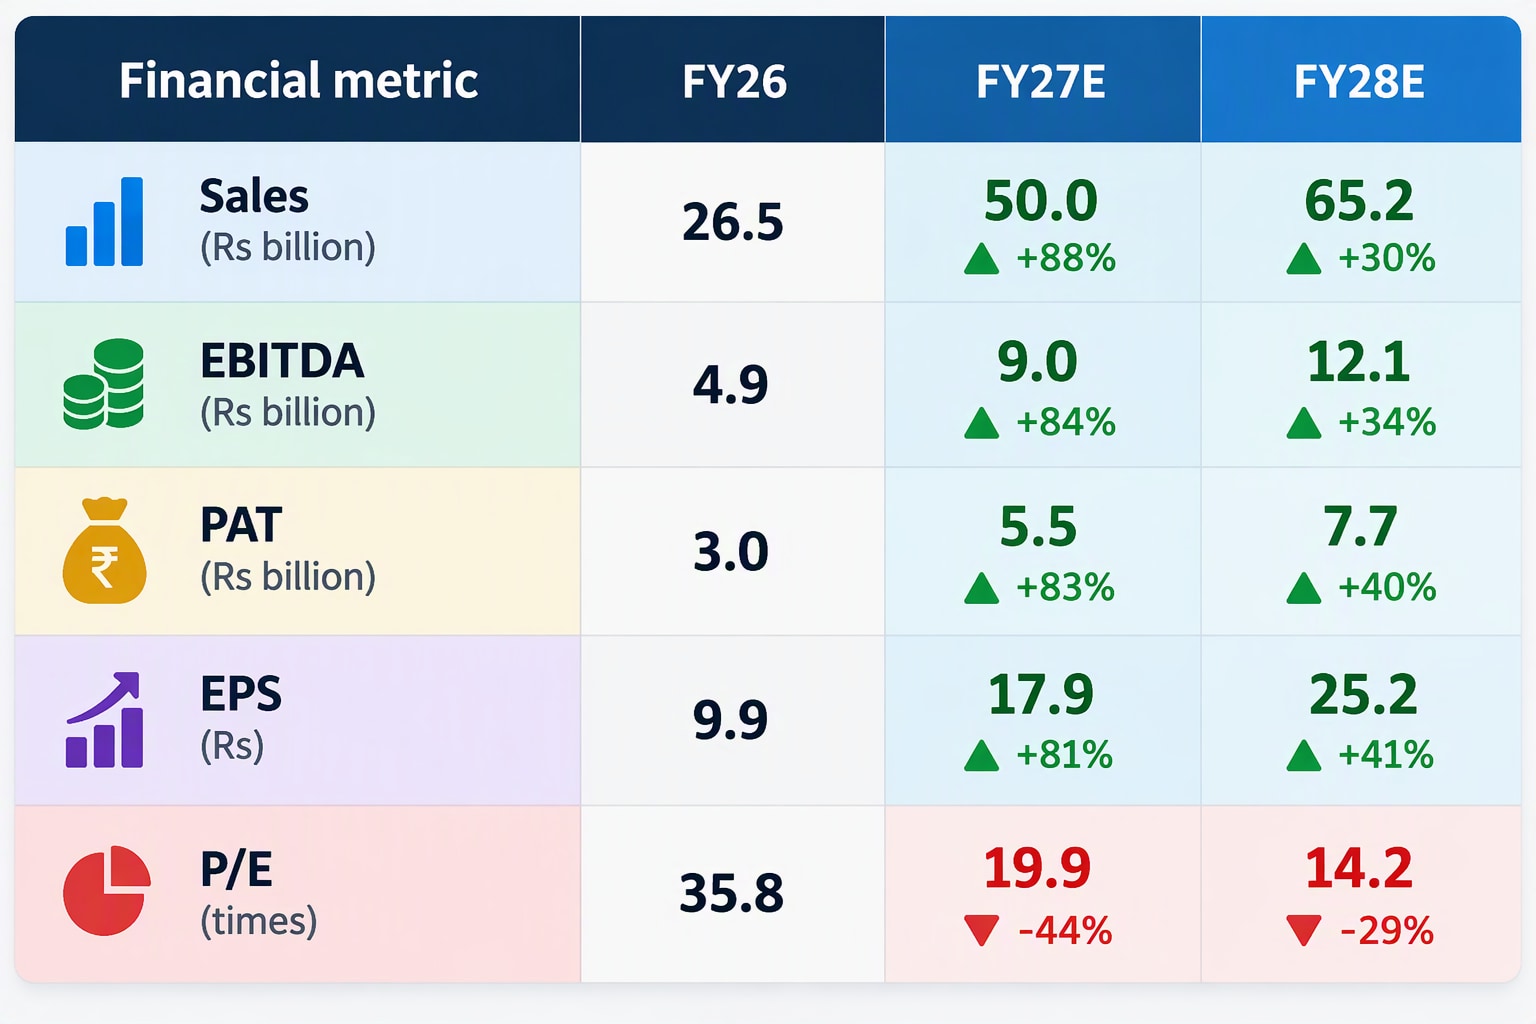
Motilal Oswal has valued the company at 20 times its estimated FY28 earnings per share. Its financial projections suggest that Fujiyama could continue delivering strong growth over the next two financial years.
New Manufacturing Plants: Where Is Fujiyama Investing?
Fujiyama is spending heavily to manufacture more components in-house instead of depending on external suppliers.
One of its major developments is the commissioning of a 2 GW power electronics facility at Ratlam, Madhya Pradesh, during Q2 FY27. The plant manufactures solar inverters, UPS systems and related products. The company's total power electronics capacity has now increased to 4.1 GW.
It is also expanding its lithium-ion battery manufacturing capacity at Ratlam from 2 GWh to 3 GWh. Once commissioned, its overall lithium-ion battery capacity will reach 3.5 GWh.
Another important project is a 1.2 GW solar cell manufacturing facility at Ratlam. The company is investing around Rs 350 crore in the project and expects commissioning by Q1 FY28. This will take its total solar cell manufacturing capacity to 2.2 GW.
The facility is particularly important because of upcoming domestic manufacturing requirements for solar installations.
Fujiyama is also setting up a new 1 GWh tubular battery plant at Hathras, Uttar Pradesh. The facility, requiring an investment of around Rs 20 crore, is expected to be commissioned by Q3 FY27. It will replace the capacity lost in the Bawal fire and reduce dependence on external battery suppliers.
The company has also increased its stake in Gio Energy and Gio Cable to 50 per cent. These entities plan to manufacture solar ribbons, junction boxes, cables and EV seats from FY28.
Management believes these investments will improve margins because several new facilities will replace components that the company currently purchases from outside suppliers.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.