[Vantage Point] Holiday dividend or market coal? What GCash could deliver by Christmas
Already have Rappler+?
to listen to groundbreaking journalism.
Emil Mercado/Rappler
Holiday dividend or market coal? What GCash could deliver by Christmas.
AT A GLANCE
- GCash is set to debut on the Philippine Stock Exchange at P6.60, with potential price movements ranging from P5.50 to P10.00 by year-end, depending on market demand and investor behavior.
- The initial trading week is crucial, with expectations of a possible price increase to around P7.40, but profit-taking could lead to volatility.
- Investors should remain cautious, as external factors and company performance could significantly impact GCash's valuation and long-term prospects.
This is AI-generated. Read the article for full context. Report any errors.
Will retail investors unwrap a plump holiday dividend this Yuletide season, or find a lump of market coal tucked inside their stockings?
With Christmas lanterns already lighting up storefronts and GCash set to make its market debut at P6.60 a share, that very question has filled our inbox.
Many readers are tempted by the prospect of owning a slice of an app they use daily to send aguinaldo (Christmas money) and settle holiday bills — and by the tantalizing wish that a quick IPO pop might bankroll their Christmas spending.
In response, Vantage Point ran a forensic valuation exercise to separate holiday cheer from cold, hard arithmetic.
Before anyone adds GCash shares to their holiday wish list, one essential qualification is in order. What follows is strictly an analytical exercise prompted by reader inquiries. It is neither a recommendation to buy, sell, or hold GCASH (the company’s ticker name), nor is it intended to sway trading behavior.
Share prices are inherently volatile beasts, particularly amid the turbulent opening weeks of a high-profile listing. Everyday investors must always make decisions tailored to their individual financial circumstances, risk tolerance, and independent research.
With that caveat firmly established, our numbers suggest an upward bias during GCash’s opening week of trading.
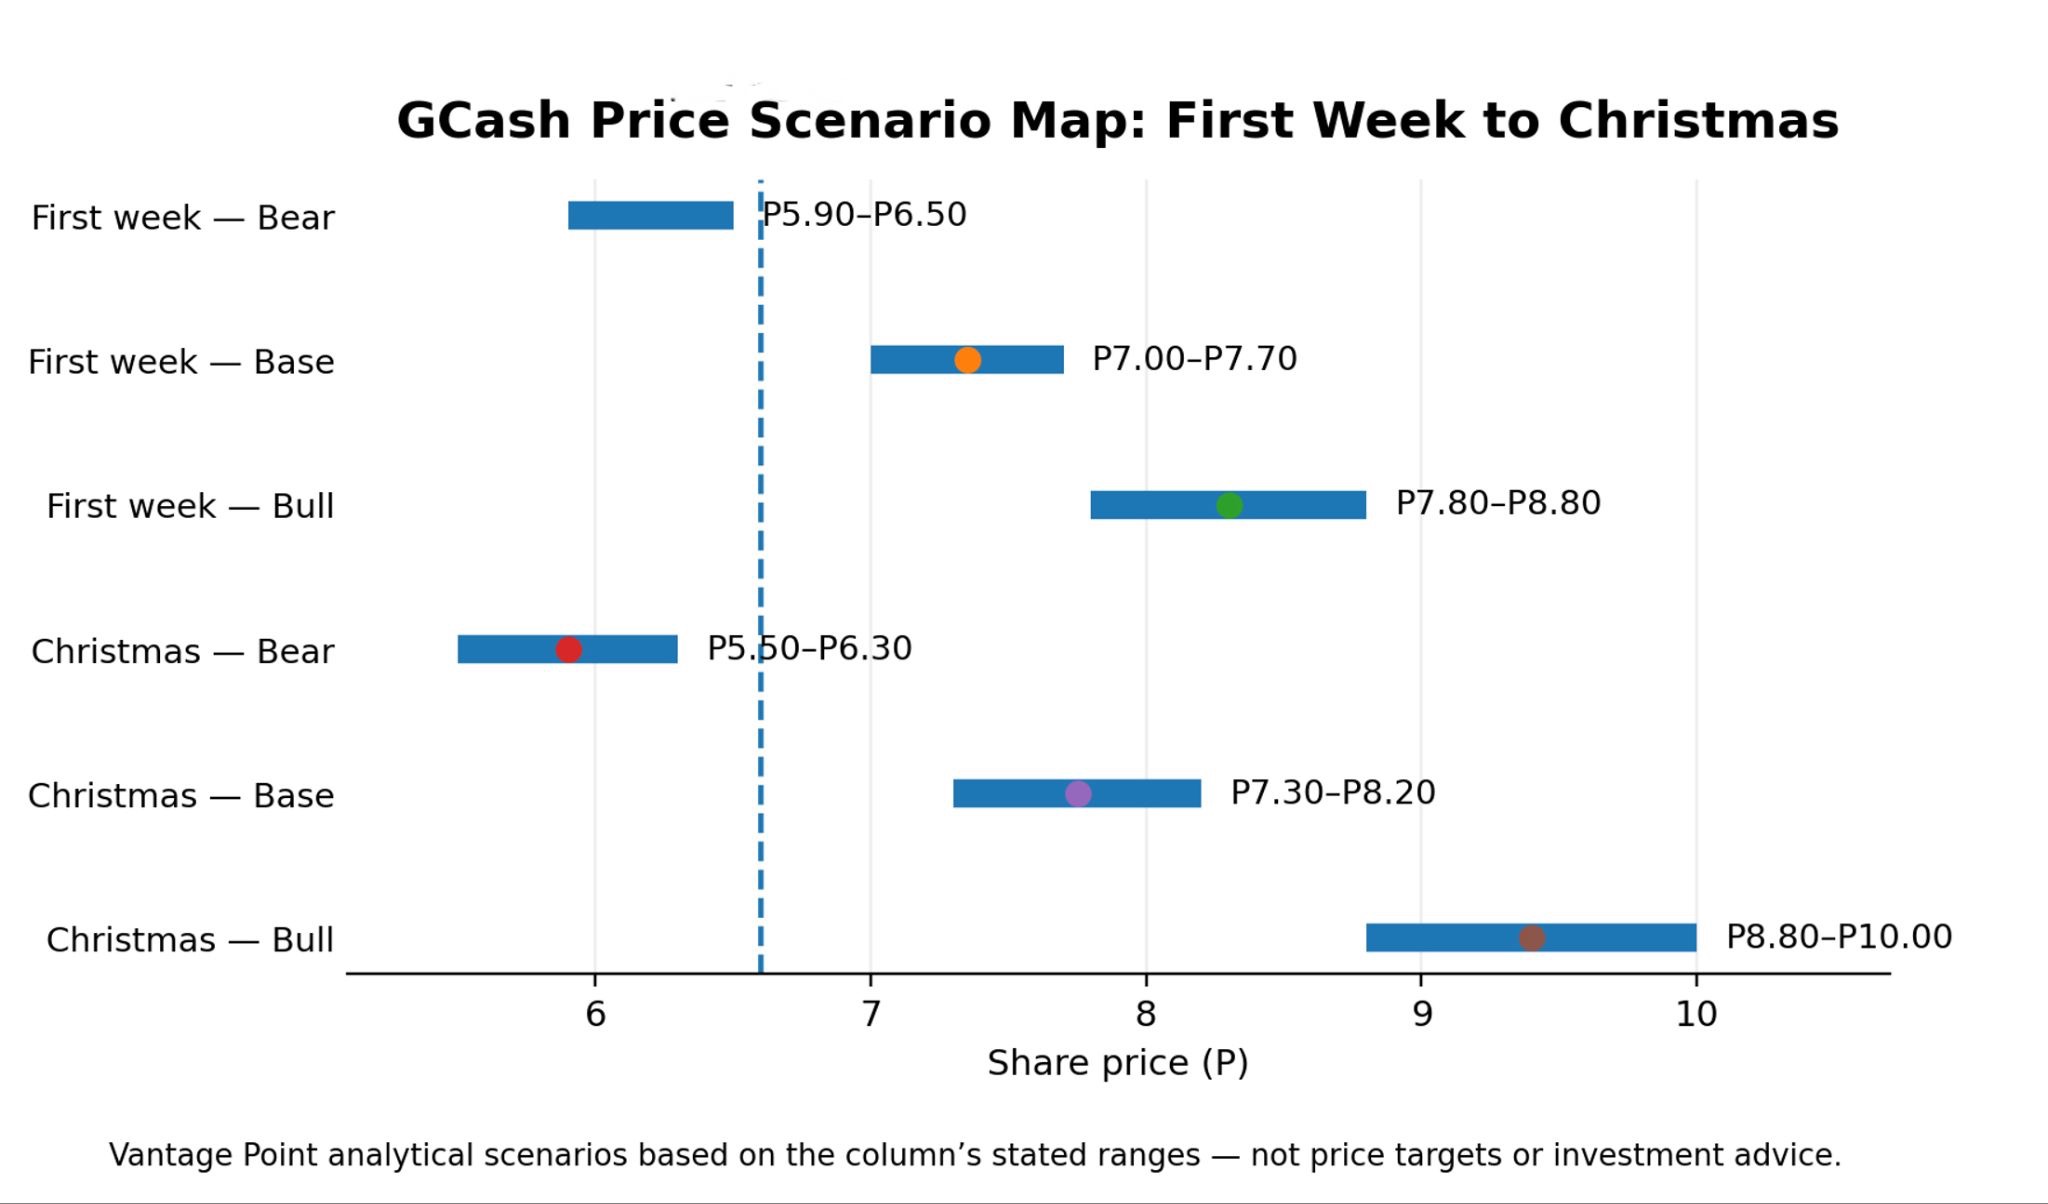
GCASH makes its formal debut on the Philippine Stock Exchange (PSE) on October 20 at P6.60. Our baseline scenario places the stock between P7.00 and P7.70 after its first full week on the boards, with roughly P7.40 serving as a sensible midpoint. That would represent a neat 12% gain from the offer price.
Under a bearish scenario, the shares could stumble toward P5.90 to P6.50. Conversely, an avalanche of pent-up demand from institutions and retail accounts could lift them toward the P7.80 to P8.80 corridor.
Unprecedented advantage
Why lean optimistic at the opening bell? Institutional bookbuilding was heavily oversubscribed, and more than 20 cornerstone investors locked in P36.5 billion in commitments. Big accounts that were scaled back or shut out during allocation often return as eager secondary-market buyers.
Moreover, GCash commands an advantage almost unprecedented for a domestic listing: an immense, captive audience. With 41.5 million monthly active users, it can present this equity offer straight to a population that already trusts its digital wallet.
Through GStocks PH, everyday retail investors can enter the fray with a board lot of just 100 shares, requiring an accessible P660 outlay at the IPO price. (READ: Want to buy GCash shares? How retail investors can join the IPO)
Yet early excitement should never be mistaken for durable value. A good portion of retail buyers will have subscribed solely to capture a quick first-day pop.
If GCASH swiftly marches toward P7.50 or P8.00, early participants sitting on double-digit paper gains may choose to cash out immediately. The opening week will inevitably become a tug-of-war between under allocated funds looking to accumulate shares and profit-takers eager to ring the register.
That makes October 27 (a full week after initial listing) a far more telling milestone than October 20.
If GCASH stays comfortably above P7.00 after several sessions of heavy churn, our base-to-bull thesis will gain genuine credibility. If it tests P8.00 and holds that ground despite waves of profit-taking, underlying institutional support is likely much stronger than conservative models assume.
On the flip side, if the stock slumps and lingers below its P6.60 offer price once official price-stabilization support winds down, it will serve as a stark warning that blowout bookbuilding numbers failed to translate into lasting market demand.
Then comes the bigger question dominating our inbox: Where might GCash settle once the Christmas holiday arrives?
Our valuation modeling outlines three distinct paths by year-end:
- The Bearish Case (P5.50 – P6.30): Cooling market momentum and slowing core operations compress multiples.
- The Base Case (P7.30 – P8.20): A balanced performance centered at P7.70, delivering a steady post-listing appreciation of roughly 17%.
- The Bullish Case (P8.80 – P10.00): Sustained retail appetite and fresh foreign inflows push valuations back toward the original ceiling.
These boundaries are anchored strictly in valuation arithmetic. At P6.60, Mynt carries an equity value of roughly P442 billion, or approximately 25.6 times its 2025 net profit of P17.25 billion. If full-year 2026 earnings reach around P21 billion — in line with its first-half performance — earnings per share across roughly 66.9 billion post-offer shares would sit near P0.31 to P0.32. At a P7.70 midpoint, GCASH would trade at roughly 24 times prospective earnings.
While that multiple commands a premium over traditional Philippine conglomerates, it remains defensible for a dominant, profitable fintech expanding into micro-lending, savings, insurance, and investments.
Yet the bears have compelling arguments. In the first half of 2026, Mynt’s net profit grew by just 7%, while core EBITDA dipped 4% and margins narrowed to 27.3%.
Furthermore, passive interest earned on its P68.6-billion cash balance jumped 45% to P2.56 billion, masking softening operating earnings. Serious investors must watch whether core platform revenue regains momentum rather than relying on bank deposit interest to carry the bottom line.
Markers to track
External variables could easily scramble these projections. A sudden downturn across the Philippine Stock Exchange (PSE), shifts in foreign capital flows, currency headwinds, or geopolitical shocks could overpower company-level fundamentals.
Even so, setting these benchmarks gives investors concrete markers to track. Our primary checkpoint is P7.00 to P7.70 one week in, followed by our year-end base band of P7.30 to P8.20.
Will GCash provide extra cash for Noche Buena (Christmas Eve feast)? Perhaps. But treating an initial public offering like a guaranteed holiday bonus is a dangerous mistake.
The true test begins on October 20, when millions of Filipinos who trust GCash with their daily funds discover whether trusting it with their investment capital yields the very same satisfaction.
I welcome your views on these and other issues where decisions made in power shape the country’s economic future.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.