E Ink cuts sales growth forecast on slow demand
By Lisa Wang / Staff reporter


E Ink Holdings Inc (元太科技), the world’s biggest e-paper display supplier, yesterday cuts its full-year revenue growth forecast for a second time to 9 percent, citing sluggish demand for consumer electronics including e-readers as surging memorychip costs drive up retail prices.
Despite the downgrade, the company still expects full-year revenue and profit to reach record highs, E Ink chairman Johnson Lee (李正昊) told an online earnings conference.
Three months ago, Lee projected revenue this year would expand at an annual rate of 10 to 15 percent from NT$36.12 billion (US$1.1 billion) last year.
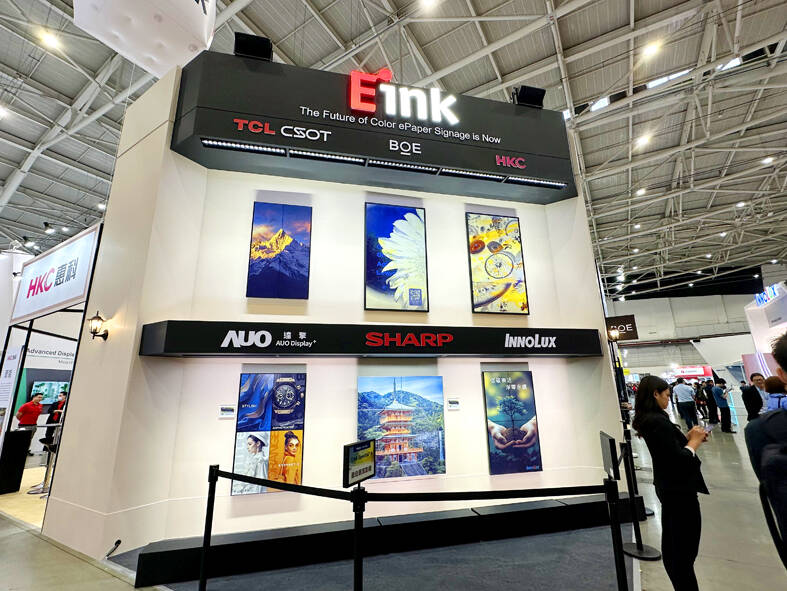
E Ink Holdings Inc’s booth at the Touch Taiwan trade show in Taipei is pictured on April 17 last year.
Photo: Chen Mei-ying, Taipei Times
“Unfortunately, we’ve fallen victim to the AI [artificial intelligence] boom,” Lee said. “Still, we remain fairly optimistic about our trajectory. Even without the AI hype, our business can continue to grow.”
Lee attributed the downgrade to a forecast 15 percent year-on-year drop in the consumer segment, but a projected 35 percent growth in the Internet of Things (IoT) business — driven by retail and electronic shelf labels (ESL) — should offset the decline.
Consequently, E Ink anticipates a structural shift in its revenue mix, as IoT sales are projected to surpass those of its consumer segment for the first time in its history, Lee said.
E Ink expects growth momentum to persist next year, fueled by robust demand for e-paper used in ESLs and digital signage, Lee said.
Growth would also be supported by improved yields on its new H5 production line, which manufactures wider films — a key material in e-paper production — resulting in a better cost structure, he said.
The company is also installing another line, H6, to produce even wider films than H5, he added.
Beyond its core e-paper display business, E Ink is expanding into polytetrafluoroethylene (PTFE) — commonly known as Teflon — through its 15.7 percent owned Taiflex Scientific Co (台虹), a leading Taiwanese supplier of flexible copper-clad laminates.
The potential shift to PTFE has become one of the hottest topics across the local printed circuit board supply chain, as Nvidia Corp looks to adopt the material for its next-generation servers.
E Ink plans to manufacture PTFE for Taiflex on a contract basis at its new factory in Taoyuan’s Guanyin District (觀音), Lee said.
The company expects PTFE production to generate a small amount of revenue next year before scaling up in 2028.
“Now that we are victims of AI in the consumer segment, we at least have to jump on the AI bandwagon through this,” Lee said.
E Ink reported NT$2.65 billion in net profit last quarter, slumping 37 percent year-on-year from NT$4.23 billion. The company attributed the decline to sagging demand for e-paper used in e-readers and e-notes. Gross margin dropped to 52.2 percent from 55.9 percent.
During the first three quarters, the company accumulated NT$9.17 billion in net profit, edging 2.45 percent lower from NT$9.4 billion in the same period last year.
Earnings per share slid to NT$7.94 from NT$8.17. Revenue dipped about 1 percent annually to NT$28.79 billion.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.