Long-term care planning: Why financial protection is only part of the picture
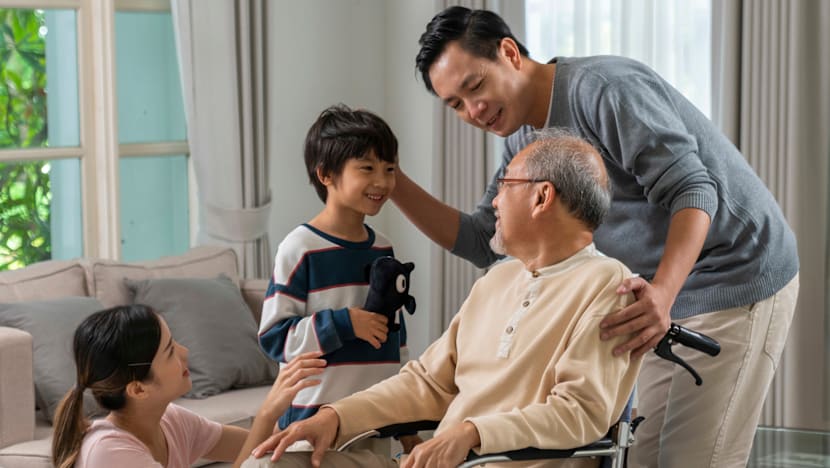
Severe disability can bring years of caregiving needs and difficult decisions. Planning ahead can help families prepare for the financial and practical demands of long-term care.
New: You can now listen to articles.

This audio is generated by an AI tool.
09 Oct 2026 09:30AM
Think of major milestones, like getting married, buying a home or having a child. People often spend years planning for these happy moments. Yet few think about preparing for one of life’s more difficult – and increasingly common – possibilities: the need for long-term care.
In Singapore, it is estimated that one in two residents could develop severe disability at some point in their lifetime¹. A critical illness or health event, such as a stroke or spinal cord injury, can occur at any age and may affect a person’s ability to work, live independently or carry out everyday activities. This can create care needs that continue well beyond hospital treatment.
The financial impact can also be significant. Treatment and recovery from a critical illness can take an average of 27 months and cost around S$169,000, according to Singlife’s Closing the Recovery Gap report². For some families, the journey may also involve rehabilitation, caregiving or longer-term support.
Yet, recovery-related needs can be overlooked. Three in five family caregivers draw on their own savings to help cover the expenses, according to the report². This makes it important for families to consider how they would fund recovery, replace lost income and meet care needs if a serious illness affects a loved one’s independence.
LONG-TERM CARE MAY COST MORE THAN EXPECTED
The impact of severe disability extends beyond hospitalisation and medical expenses. It can bring emotional strain and caregiving needs, along with additional costs for mobility aids, home nursing, professional caregivers and senior care centre services. These pressures can be especially challenging for the sandwich generation – middle-aged adults who are raising children and supporting ageing parents.
A 2025 long-term care white paper by Singlife found that 57 per cent of Singaporeans underestimate the cost of long-term care, which averages S$2,952 a month over a 10-year period. Singlife’s youngest claimant was just 32 at the time of his claim.
For Singapore citizens and permanent residents (PRs), CareShield Life offers basic protection against long-term care costs. The national long-term care insurance scheme provides monthly cash payouts for life in the event of a severe disability, defined as being unable to perform at least three out of six activities of daily living (ADLs) – washing, dressing, feeding, toileting, transferring from one position to another, and walking or moving around.
To help keep pace with rising long-term care costs, CareShield Life is being enhanced. Between 2026 and 2030, monthly payouts will increase by 4 per cent each year, up from 2 per cent previously. Premiums will also increase over the same period, with subsidies for lower-income policyholders.
Even with these enhancements, however, the basic payouts may not cover the full cost of long-term care. With average monthly expenses approaching S$3,000, families could still face a funding gap.
BRIDGING THE LONG-TERM CARE GAP WITH ENHANCED FINANCIAL SUPPORT
Singapore citizens and PRs can supplement CareShield Life with private insurance for additional coverage. Two options are Singlife CareShield Standard and Singlife CareShield Plus, which provide additional monthly payouts of up to S$5,000 if severe disability occurs.
Under Singlife CareShield Standard, policyholders can start receiving support when they are unable to perform at least two ADLs, compared with CareShield Life’s threshold of three. Under Singlife CareShield Plus, payouts begin when a policyholder is unable to perform at least one ADL.
To reduce out-of-pocket expenses, premiums for both plans can be paid using MediSave, subject to the prevailing annual withdrawal limit of S$600. In certain situations, premiums may be waived if a policyholder develops a mild disability.
Other benefits include a lump-sum payout upon severe disability and financial assistance for caregiving expenses.
Taking up supplementary coverage at a younger age may mean lower premiums at the point of enrolment. Applying while in good health could also reduce the likelihood of future health conditions affecting eligibility or coverage.
WITH SINGLIFE, SUPPORT GOES BEYOND INSURANCE PAYOUTS
Financial protection is important, but navigating a serious illness or disability can require more than money alone.
Singlife Care Collab, a one-stop health services hub, connects Singlife protection policyholders with healthcare providers and support services. Through the platform, they can access a network of partners offering caregiving resources, rehabilitation support and community services, as well as discounts and privileges.
Customers who purchase Singlife CareShield Standard or Plus together with a qualifying Singlife critical illness plan or rider are eligible for enhanced payouts for caregiving needs. The Caregiver Relief Benefit can be extended from 12 months to 36 months, providing up to three times the standard payout period.
The broader objective is to improve overall well-being, said Ms Helen Shen, group head of products at Singlife. “We are looking beyond financial planning by providing tailored assistance and connecting our customers with Singlife Care Collab partners. We aim to ease the burden on their families and support them throughout their recovery from disability.”
Start planning for critical illness coverage and long-term care early, so you and your family are better prepared for the challenges ahead.
Products’ terms and conditions apply. These policies are underwritten by Singapore Life. This is published for general information only and does not have regard to the specific investment objectives, financial situation and particular needs of any specific person. You should read the product summary and seek advice from a financial adviser representative before making a commitment to purchase the product. Singapore Life accepts no liability whatsoever with respect to the use of this article or its contents.
To find out more about Singlife products, visit singlife.com. This advertisement has not been reviewed by the Monetary Authority of Singapore. Protected up to specified limits by the Singapore Deposit Insurance Corporation. The information contained in this article is accurate as at Oct 9, 2026.
¹Ministry of Health, CareShield Life. Last updated on Dec 23, 2025.
²Singlife, Closing the Recovery Gap: Insights from the Singlife Critical Illness Study 2026. Published in August 2026.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.