BoG to issue new Credit Risk Directive as NPL ratio in the Savings and Loans sector deteriorates
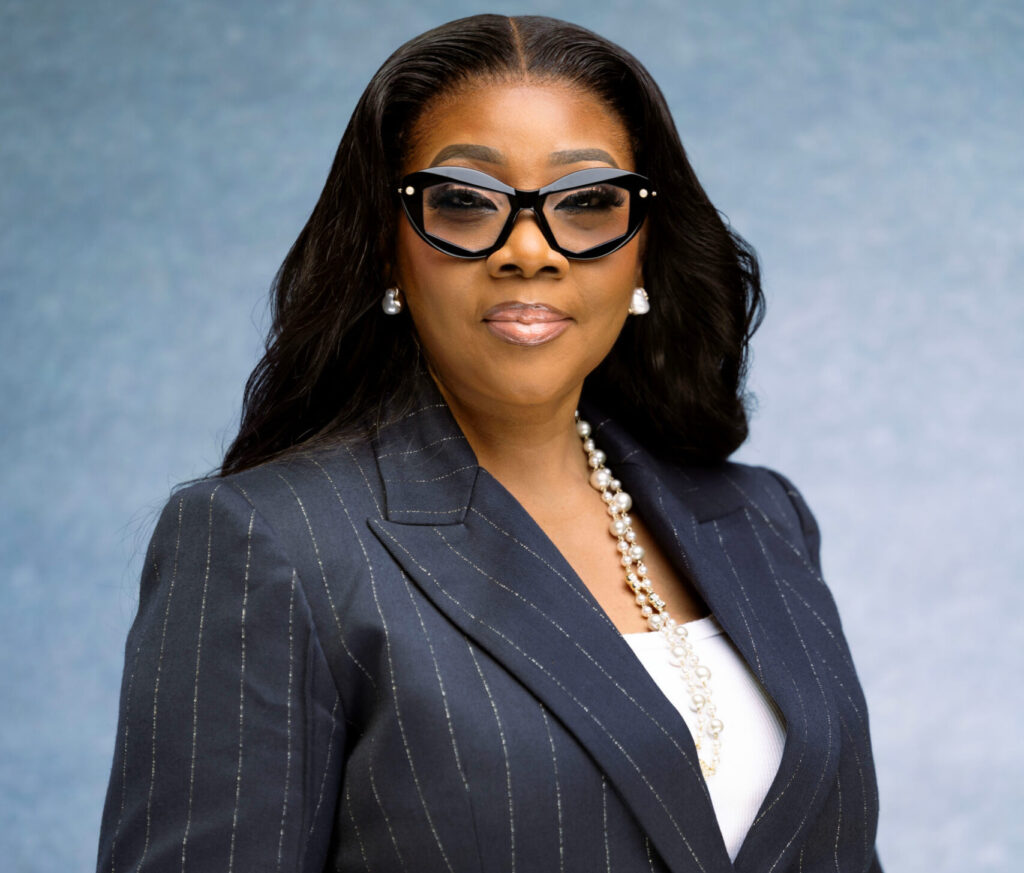
The Bank of Ghana (BoG) has announced plans to issue a Credit Risk Management Directive to strengthen lending practices, improve loan recovery and address rising non-performing loans (NPLs) in the financial sector.
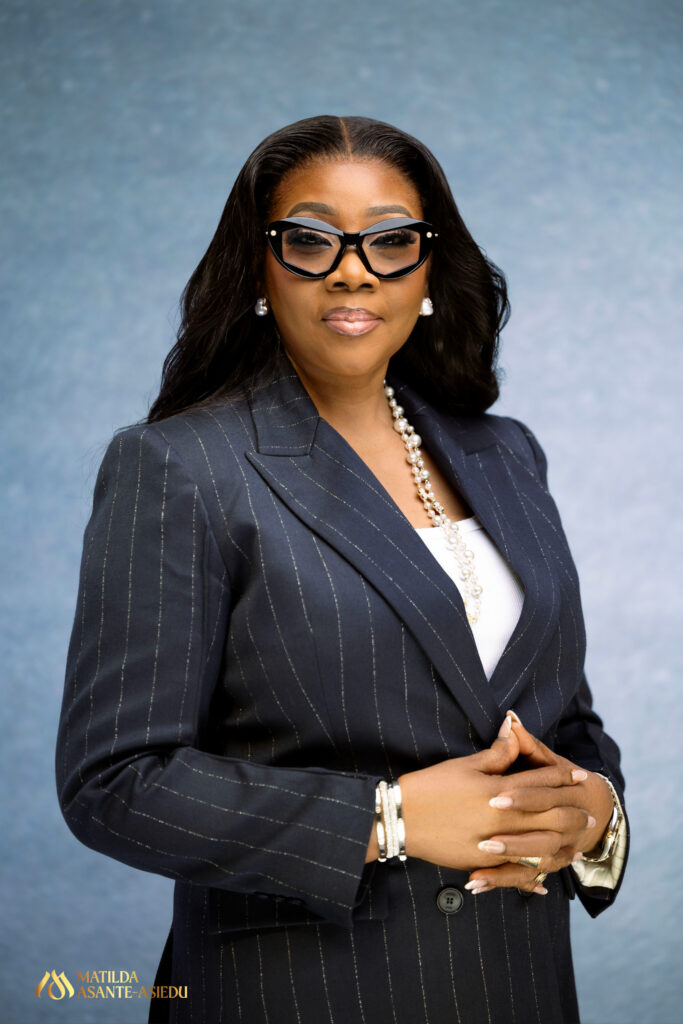
Second Deputy Governor Mrs Matilda Asante-Asiedu announced this on Wednesday, October 7, at the commissioning of Advans Ghana Savings and Loans’ new head office in Dzorwulu, Accra. She said the directive would require Regulated Financial Institutions (RFIs) to establish robust credit risk management frameworks covering credit underwriting, loan administration, risk measurement, monitoring, and recovery.
“This directive aims to ensure that Regulated Financial Institutions (RFIs) develop and implement appropriate frameworks for managing their credit risk by establishing a robust credit risk environment; a sound credit-underwriting process; and maintaining appropriate credit administration, measurement, monitoring, and recovery processes and functions.”
The directive will also set clear requirements for how institutions assess borrowers, manage credit risk and monitor loans, to reduce the accumulation of bad debts.
Savings and loans NPLs rising against the industry trend.
The announcement comes as the savings and loan sub-sector faces growing pressure to improve its loan portfolios. The BoG expects RFIs to bring their NPL ratios down to no more than 10% by the end of December 2026. Even as the industry-wide ratio improved, the sub-sector’s deteriorated.
“The banking industry’s ratio stood at 16.1 per cent at end-June 2026, down from over 23 per cent a year earlier. However, for the Savings and Loans sub-sector, the NPL deteriorated from 15.35% in June 2025 to 19.44% for the same period in 2026. So, there is real work ahead of us in this last quarter to bring this in line with the regulatory expectation,” she said.
The Deputy Governor noted that the BoG’s 2025 Notice on Non-Performing Loans had already set supervisory expectations for credit risk governance, prudential limits for NPL ratios and remedial measures for willful defaulters. The new directive reinforces these measures by requiring stronger credit risk management systems and more effective oversight of lending across the loan cycle. It complements existing regulatory measures to improve asset quality and strengthen the financial system.
Broader reforms of the savings and loans and microfinance sub-sectors
MMrsAsante-Asiedu said the directive is part of wider reforms to the savings and loans and microfinance sub-sectors. These sub-sectors, she said, have extended financial services to young people, women and micro, small and medium-sized enterprises (MSMEs), and have supported employment and financed businesses often overlooked by conventional banks. She stressed that a sector carrying that responsibility must be strong enough to bear it, which is why the BoG is reforming it.
Under the reforms, the former Tier 1 to Tier 4 classification will be replaced by four categories, each with a defined mandate:
- Microfinance Banks
- Community Banks
- Credit Unions
- Last Mile Providers
Existing savings and loans companies may transition into Microfinance Banks, which will be deposit-taking institutions serving MSMEs, groups and individuals.
The reforms are to improve regulatory consistency, reduce opportunities for regulatory arbitrage and strengthen governance. Institutions in the same category will be held to the same standards, and boards and management teams will be required to demonstrate the necessary skills, expertise, and ethical standards. The Second Deputy Governor said the reforms should rebuild public confidence, deepen financial inclusion, attract investment, and strengthen local participation and ownership.
December capital deadline
Mrs Asante-Asiedu reminded existing institutions seeking to become Microfinance Banks that they have until December 31, 2026, to meet the minimum capital requirement of GH¢50 million. New entrants must meet GH¢100 million. Institutions may meet the requirement independently; merge with, or be acquired by, another institution; transfer their assets and liabilities to a qualified institution through an orderly process; or exit voluntarily.
She commended Advans Ghana for its commitment to meeting the new capital requirements and praised the Advans Group for supporting its Ghanaian subsidiary.
“We encourage other foreign shareholders to show a similar level of commitment to support their Ghanaian subsidiaries as all institutions work towards the end-of-year deadlines, for capital and for non-performing loans alike.”
She called on financial institutions, government agencies, development partners, and customers to support the reform process, stressing that success depends on collective commitment to compliance, transparency, innovation, and professionalism.
“The aim is a sector in which every institution is strong enough to protect its depositors and keep serving its clients.”
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
Tags:
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.