Fertiliser sales see sharp dip as El Nino dries up farm demand
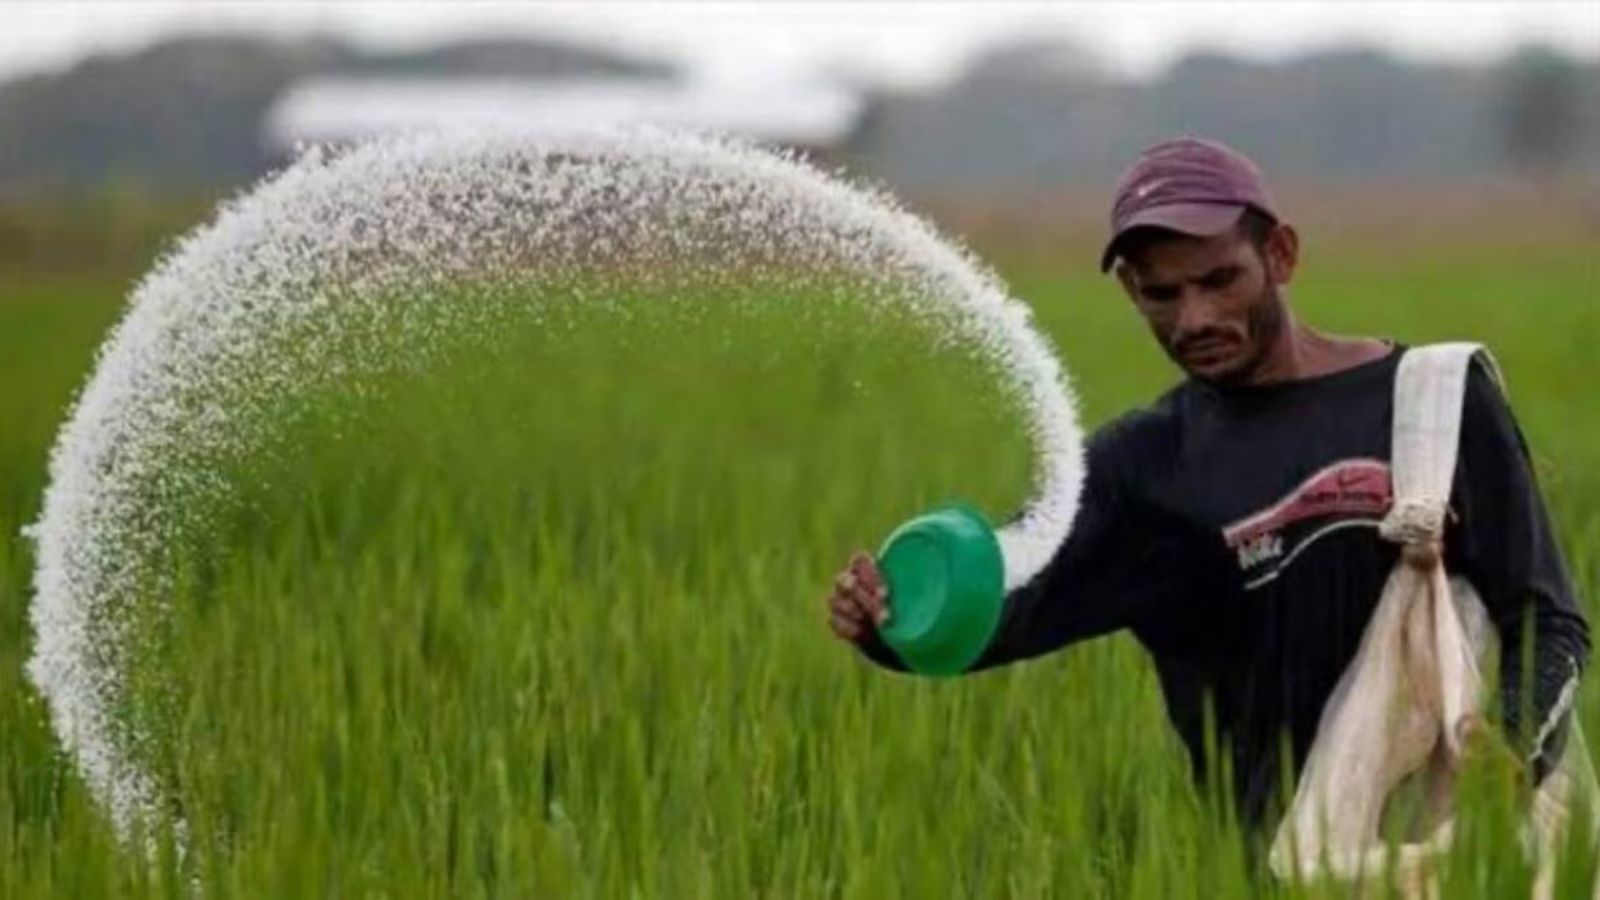
In what could be a real indicator of deficient rains and the El Nino effect on farms, domestic sales of all fertilisers, including urea, are down compared to last year.
The sales drop during April-September 2026 over April-September 2025 — roughly coinciding with the kharif (monsoon) planting season — has been the sharpest at 22.2% for complex fertilisers containing nitrogen (N), phosphorus (P), potassium (K) and sulphur (S) in different ratios, followed by 11.7% for muriate of potash (MOP).
The declines have been much lower, at 0.6% and 1.4% respectively, for di-ammonium phosphate (DAP) and single super phosphate (SSP).
A more significant fallout, reflective of subdued farmer offtake from the El Niño-induced dry weather conditions, is that of urea.
According to data from the Fertiliser Association of India (FAI), both production and imports of this most widely consumed nitrogenous fertiliser during April-September 2026 have been 4.3% and 40.5% higher relative to their corresponding April-September 2025 levels.
This comes on the back of the Government’s concerted efforts at boosting imports of liquefied natural gas to ensure adequate feedstock availability for domestic urea manufacturers. State-owned companies have been pushed not only to source more gas from the US, Nigeria, Oman, Angola, Cameroon, Australia and Norway — to offset dwindling supplies from Qatar and UAE because of the Iran war and closure of the Strait of Hormuz — but also float international tenders for direct imports of the fertiliser.
The resultant increased availability notwithstanding, urea sales are 4.1% down year-on-year (see table), marking the first dip after 2021-22 and from the record 39.6 million tonnes of 2025-26 (April-March).
Story continues below this ad
“The main reason is poor rains across the southern states, Maharashtra’s Marathwada and Vidarbha regions, Saurashtra and Kutch in Gujarat, Rajasthan, south Bihar, and Assam. It has led to lower demand from farmers. Last year, many of them paid Rs 350-450 per 45-kg bag of urea, as against its official maximum retail price (MRP) of Rs 266.50. This time, the black-market rate has been within Rs 300, as there is no physical shortage of material or much desperation among farmers to stock up,” an industry source told The Indian Express.
Rainfall during the southwest monsoon season (June-September) was 12.6% below the normal long-period average for the country as a whole. October, too, has registered an overall 51.8% rain deficiency so far.
Most global weather agencies are forecasting the present El Nino to persist as a strong-to-very strong event through January-March 2027, before turning moderate-to-weak towards April-May. Subpar winter precipitation and higher-than-usual temperatures from El Nino could, in turn, impact crop plantings and fertiliser demand for the upcoming rabi (winter-spring) season, as well.
“The Government’s focus now is just on urea and DAP. It does not want any shortage in these two politically most-sensitive fertilisers, especially in Uttar Pradesh and Punjab that are headed for Assembly polls in February-March,” the industry source said.
Story continues below this ad
In DAP, too, the supply position is reasonably comfortable, with sales happening at around or marginally above the government’s controlled MRP of Rs 1,350 per 50-kg bag.
That is, however, affecting the offtake of complex fertilisers. Their MRPs are ruling higher at about Rs 2,100 per bag for the ‘20:20:0:13’ and Rs 2,400 for ‘12:32:16’ and ‘10:26:26’ NPKS grades.
“Complex fertiliser sales are being hit from both the demand and supply sides. On the one hand, we have drought and the government setting an artificially low MRP for DAP, despite it having a higher 46% P and 18% N content. On the other, there is an acute scarcity of sulphur, without which no manufacturing of any P-containing complexes or even SSP can take place,” the source said.
FAI data shows domestic production of complex fertilisers and SSP plunging by 35.5% and 10.4% respectively in April-September 2026 over April-September 2025. This has been largely courtesy of the soaring import prices of sulphur ($1,000-1,100 per tonne versus $300-400 a year ago).
Story continues below this ad
Sulphur is a byproduct of oil refining and natural gas processing. Prior to the war, India was importing sulphur mainly from the likes of Saudi Aramco, QatarEnergy and Abu Dhabi National Oil Company, whose facilities have suffered damage from Iranian missile and drone attacks.
But it’s not fertilisers alone.
Domestic despatches of tractors also fell 18.1% to 1,19,667 units in September, from 1,46,180 for the same month of last year. Tractor sales hit an all-time-high of 11.60 lakh units in 2025-26. The first six months of this fiscal, too, also posted a cumulative 8% growth over April-September 2025.
An executive from a leading tractor and farm equipment company, however, attributed the September sales decline more to a shift in the festival season calendar and base effect.
“Last year, the season began early with Raksha Bandhan on August 9 and Navratri-Dussehra got over by October 2. This time, Raksha Bandhan was on August 28 and Dussehra on October 20. The GST rate cut on tractors (from 12% to 5%) also took effect in September 2025. Both these factors drove up industry shipments by 45.4% year-on-year last September,” he said.
Story continues below this ad
The executive said that drought was still a concern and “we have to see whether and how much our sales get impacted in the remaining months of this fiscal”.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.