Reverse mortgage growth defies lull
LONG HORIZON: Banks favored homes in established urban districts with stronger resale prospects, while women accounted for nearly 58 percent of approved loans
By Crystal Hsu / Staff reporter


Taiwan’s reverse mortgage business continued to expand in the first nine months of this year, as older homeowners increasingly used their properties to supplement retirement income, although new lending slowed in the third quarter, Financial Supervisory Commission (FSC) data showed.
Banks had approved a cumulative total of 11,285 reverse mortgage loans worth NT$67.8 billion (US$2.09 billion) as of Sept. 30, with their combined value up 16.3 percent from a year earlier, the data showed.
However, banks approved only 274 new loans worth NT$2.187 billion in the third quarter, with the number of cases falling below 300 for the first time in about two years, according to the commission.
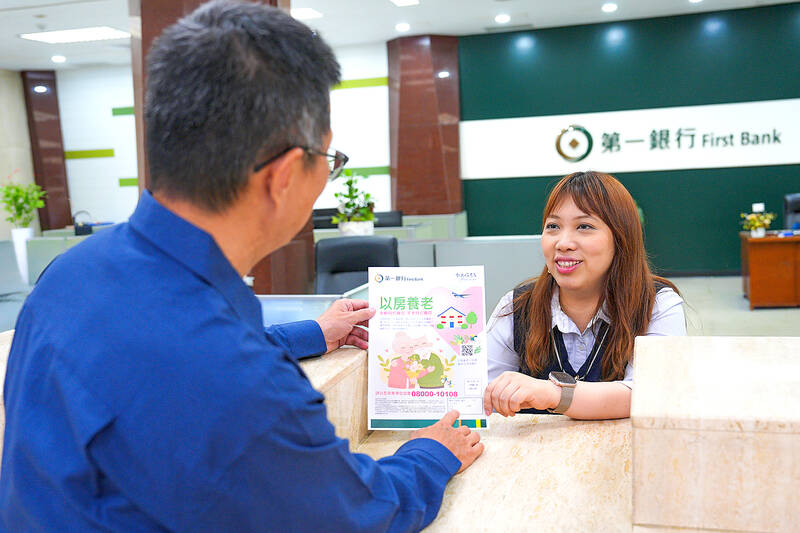
A First Commercial Bank employee hands a reverse mortgage brochure to a customer in Taipei in an undated photograph.
Photo courtesy of First Commercial Bank
Property consultancy Colliers International Taiwan (高力國際) attributed the slowdown partly to higher market interest rates and a cooling housing market, saying lenders had become more cautious about property valuations and the long-term risks of reverse mortgages.
Although the central bank has kept its policy rates unchanged, rising market borrowing costs have pushed up reverse mortgage lending rates, reducing the monthly payments available to borrowers and making the product less attractive to some older homeowners, Colliers Taiwan said.
Reverse mortgages allow homeowners to receive regular payments against the value of their properties while continuing to live in their homes.
The loans provide an additional source of retirement income for older people who own property but have limited cash savings, allowing them to remain financially independent without selling their homes or relying entirely on support from their children.
Unlike conventional mortgages, reverse mortgages require lenders to assess how property values and resale prospects might change over an extended period. With loan terms averaging more than 22 years, the long-term value and marketability of a property are key considerations.
Banks have increasingly favored homes in established urban districts, where properties are generally easier to resell, while taking a more conservative approach to lower-priced homes in less central locations and properties bought primarily for investment.
The Greater Taipei area accounted for the largest share of approved loans, reflecting the concentration of property wealth in the region. Women accounted for nearly 58 percent of approved loans, FSC data showed.
Taiwan Cooperative Bank (合作金庫銀行) led in the number of approved loans, followed by Land Bank of Taiwan (土地銀行), Hua Nan Commercial Bank (華南銀行) and First Commercial Bank (第一銀行).
Each of these four government-backed banks had approved more than 1,000 loans cumulatively as of Sept. 30, the data showed.
In the first nine months, the average amount approved per loan rose 8 percent from a year earlier to NT$7.77 million, while the third-quarter average stood at NT$7.98 million, little changed from NT$8.03 million in the second quarter, indicating that the slowdown in new approvals did not translate into a comparable decline in average loan size.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.