French borrowing costs overtake US amid budget turmoil
French borrowing costs continued to rise on Thursday, as investors fret that France’s government is struggling to pass a federal budget after public protests gripped the country.
France’s bond market was hit with another bout of selling, with the difference between French and German 10-year borrowing costs – a metric for the risk premium attached to French debt – rising to its highest level in almost 15 years.
The yield on the French 10-year bond – known as obligation assimilables du Trésor (Oat) – rose by nine basis points to 5.089% in early trading on Thursday, its highest level since July 2022. It broke across the 5% threshold on Wednesday for the first time since 2002.
The move lifted France’s 10-year borrowing costs over the equivalent for US Treasury bonds for the first time since 2013.
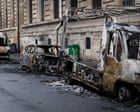
The volatility comes as the French government struggles to pass a budget for next year, while the country recovers from widespread protests that turned violent last weekend.
Tens of thousands of people had attended peaceful marches to demand more teachers and repairs to decrepit schools, but different groups clashed with police in cities including Paris, Bordeaux, Nice and Marseille in recent days.
Public buildings were attacked, and thousands of shops and businesses were looted. The interior ministry said there had been nearly 2,400 arrests.
Meanwhile, a parliamentary gridlock has blocked the president Emmanuel Macron’s plans to increase the state pension age from 62 to 64 and a series of measures designed to rein in state spending.
France’s budget deficit was 5.1% of gross domestic product in 2025, while its debt pile stood at 115.6% of GDP.
It comes as the country also grapples with higher inflation triggered by the war in Iran, with many governments with big debt piles coming under acute pressure.
Jim Reid, a market strategist at Deutsche Bank, said the sell-off in French government bonds was starting to ripple out to other countries, too.
after newsletter promotion
“Among others, the Italian 10-year spread over [German bonds] widened 3.8 basis points to 116 basis points, while Spain’s widened 3.1 basis points to 66 basis points, marking its widest level since June 2025,” he said.
Carsten Brzeski of the bank ING said rising yields had reinforced the European Central Bank’s “restrictive” monetary policy stance before its interest rate decision next week. The bank last raised its key interest rate to 2.5% in September.
“The ECB is very likely to stay on hold next week and will delay any next rate hike decision to December,” he said.
“Any solution to the current French fiscal woes could bring some relief to bond markets and allow the ECB to continue hiking rates. Without any solution, bond markets have taken over the ECB’s role, making rate hikes less likely.”
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.