THE FINANCIAL WELLNESS COACH: Weighing up rental income against long-term investment growth
I have a rental property worth R5.5-million that generates an income of R46,000 a month. After expenses, I am left with R32,650. As I don’t need the income, I invest the rental proceeds in a balanced fund that returns 10% a year.
I am considering selling because of developments in the neighbourhood that could negatively affect property values. If I sell, I should clear about R5-million. Would I be better off keeping the property and investing the rental income, or selling and investing the proceeds?
Answer:
This is an interesting question because you have a property that produces a very attractive rental income. However, there is more to owning property than collecting rent. We also need to consider what the property may be worth in 10 years, the tax you pay on the rental income and whether your money could work harder elsewhere.
Let’s look at the two options and see where you might end up after 10 years.
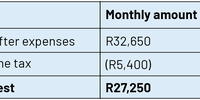
First, let’s look at the tax. Your property generates R32,650 a month after expenses. Unfortunately, the South African Revenue Service also wants its share.
Assuming this is your only taxable income and that you are under 65 and have no other deductions or tax credits, your position would look roughly as the following table shows.
Option 1: Keep the property and invest the rental income
Let’s assume you keep the property and invest R27,250 in a balanced fund each month. At an average return of 10% a year, your investment would grow to about R5.2-million after 10 years.
Importantly, you would still own the property. If the property remained worth R5.5-million, your combined assets would amount to about R10.7-million.
Option 2: Sell the property and invest the proceeds
You mentioned that you expect to receive about R5-million after selling costs. Let’s assume you invest the R5-million in the same balanced fund, earning an average return of 10% annually. After 10 years, it would be worth about R13-million.
Let’s compare the two after 10 years, assuming your property’s value remains unchanged (see the table below).
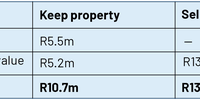
So, if the new neighbourhood developments do result in a decline in property values, it would make sense to sell and reinvest elsewhere. However, if property prices were to increase, then keeping the property would make sense. I ran some scenarios, and if the property value increased by more than 4% a year, keeping the property would provide a better return.
Remember that these projections are illustrative. I have assumed that rental income and expenses remain unchanged. The figures also exclude investment taxes, fees and any capital gains tax on the property. Before you do anything, I would recommend speaking to a financial specialist who can accurately model the options for you.
There is one other factor I would take seriously. You have R5.5-million invested in a single property in a single neighbourhood. If the area deteriorates, property prices fall or you struggle to find tenants, your investment could suffer.
A balanced fund spreads your money across different investments, including local and international shares, bonds and cash. That doesn’t mean there is no risk. Investment markets can have some very difficult years. However, you are no longer dependent on what happens to just one property.
There is also the benefit of having access to your money. With a balanced fund, you can generally withdraw a portion of your investment without selling the rest.
I can see a good case for selling, particularly given your concerns about the neighbourhood. However, I would not rush into it. You have a property producing an attractive rental income, and it may still provide good capital growth over the next 10 years.
Ultimately, the question isn’t whether your property is a good investment. It clearly is. The question is whether it will remain the best place for your R5.5-million over the next 10 years. DM
Kenny Meiring is an independent financial adviser. Contact him on 082 856 0348 or at financialwellnesscoach.co.za. Send your questions to kenny.meiring@sfpadvice.co.za
This story first appeared in our weekly DM168 newspaper, available countrywide for R39. The e-edition of Daily Maverick’s weekly newspaper, DM168, is now free for readers who are signed into their Daily Maverick account. Click here to access the e-edition.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.