Carney’s second budget will aim to help small businesses cut costs and invest more, sources say
OTTAWA — Prime Minister Mark Carney’s second budget is expected to include measures for Canada’s small businesses that will aim to both trim costs and encourage investment, government sources say.
Sign In or Create an Account
After announcing its productivity mega-deduction earlier this year to lower taxes on capital investments, especially large ones, National Post has learned that the Liberal government will try to help Canada’s smaller businesses cut costs in the upcoming budget.
The government is considering measures such as lowering the small-business tax rate (9 per cent), cutting red tape on such things as tax filing, and reducing the employment insurance (EI) premium rate on smaller operations, a government source said.
And on the business investment side, considered a key metric in boosting the sector’s productivity and growth, the government is also weighing the pros and cons of various policy options. On the table are measures such as expanding and accelerating a company’s ability to use capital cost allowance (CCA) provisions to write off expenses and depreciable assets, such as equipment and buildings.
And while there is still time to insert or remove items from the budget, one source said it’s very likely that the Nov. 5 document will include items to help small businesses with both costs and investment.
“You can walk and chew gum at the same time,” the source said.
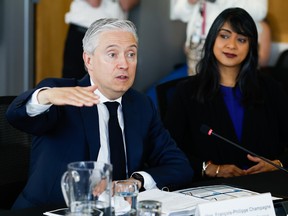
Finance Minister François-Philippe Champagne said on Wednesday that the government’s first priority in making this budget is Canadians’ cost of living. But the second, he said, is economic growth, with the accent on helping small and medium-sized businesses seize opportunities.
The Canadian Federation of Independent Business (CFIB), which represents small and medium-sized businesses across the country, warned Thursday that much of Canada’s small business sector is at risk. Nearly two-thirds (63 per cent) of small business owners plan to leave their businesses over the next decade, the organization said in a new report, but only 6 per cent of those owners have a formal succession plan in place.
CFIB has been lobbying the government to make bold changes in this budget, including a cut in the small business income tax rate to 6 per cent, from 9 per cent.
Many economists argue that the current gap between 9 per cent and the general business rate of 15 is already too much of what they consider a distortion, which encourages companies to split themselves into smaller entities and discourages growth.
The business group has also asked Ottawa to increase the small business deduction, which is the threshold for business income that qualifies for the lower tax rate, to $700,000 from $500,000.
One of the main problems in the sector, CFIB said, is that there simply aren’t enough Canadians who want to own their own business. There’s an “entrepreneurial drought” at the beginning of the cycle, the group said, and not enough buyers when a business owner wants to retire or do something else.
According to CFIB, business exits in Canada have outpaced new entries since early 2024, which is a big problem.
“A successful handover keeps a business open and brings a new generation of entrepreneurs into the economy,” Corinne Pohlmann, CFIB’s executive vice-president of advocacy, was quoted as saying in a release. “Which is why governments need to pay attention and help make it easier to buy and sell a business.”
Carney has raised the challenges of the Canadian economy’s mediocre productivity, a metric that reflects a country’s standard of living, and the lack of corporate investment. While last month’s productivity mega-deduction initiative and budget moves for small business would create extra incentives on both fronts, the government is also facing another large deficit and escalating debt.
Champagne has indicated in recent months that the government will continue to err on the side of what he calls “investments” in the economy, instead of reducing the deficit. Champagne argues that Canada has the strongest fiscal position in the G7 and that leaves room to spend or cut taxes or other revenue sources, although some analysts say that position isn’t necessarily something to brag about.
“I think Canadians can understand that we have a strong fiscal position and we’re investing in the things that will generate growth to the country,” he said in July.
The proposed new mega-deduction, which the government estimates will cost the treasury $36.5-billion over the next five years, could also be included in the upcoming budget. Whether it’s included or presented as separate legislation, the measure will be one of the government’s biggest swings at boosting long-term growth.
The government hopes that the deduction changes, announced last month at an international investors’ summit in Toronto, will spur investment, particularly in capital-intensive industries such as energy, mining, transportation, and technology. The changes are expected to cut Canada’s projected tax rate on new investment, a key metric for large investors, by slightly more than half, to about 6.4 per cent from 13 per cent.
A government source emphasized that the mega-deduction will also help small and medium-sized businesses, on top of other moves the Carney government has already made: its buy-Canadian policy, removing the federal tax on gas and diesel, eliminating the federal portion of inter-provincial trade barriers, and others. But all of those policies, combined with an array of spending moves, has left Ottawa facing another massive deficit and a greater pile of red ink.
In the government’s spring update, Champagne said the 2025–26 deficit was projected to be about $66.9 billion, down from the $78.3 billion that had been projected in last fall’s budget. That drop was due largely to a fiscal windfall from higher oil prices.
While Ottawa has been amassing large piles of debt for more than half a century, the problem has grown substantially over the last few years. The federal government has now accumulated more than $1.3 trillion in total debt, almost half of which has been added over the last five years.
National Post
Our website is the place for the latest breaking news, exclusive scoops, longreads and provocative commentary. Please bookmark nationalpost.com and sign up for our daily newsletter, Posted, here.
Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.
KioskNews shows a cleaned-up reading view extracted from the publisher’s page — the original always lives on their site, not ours.